Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
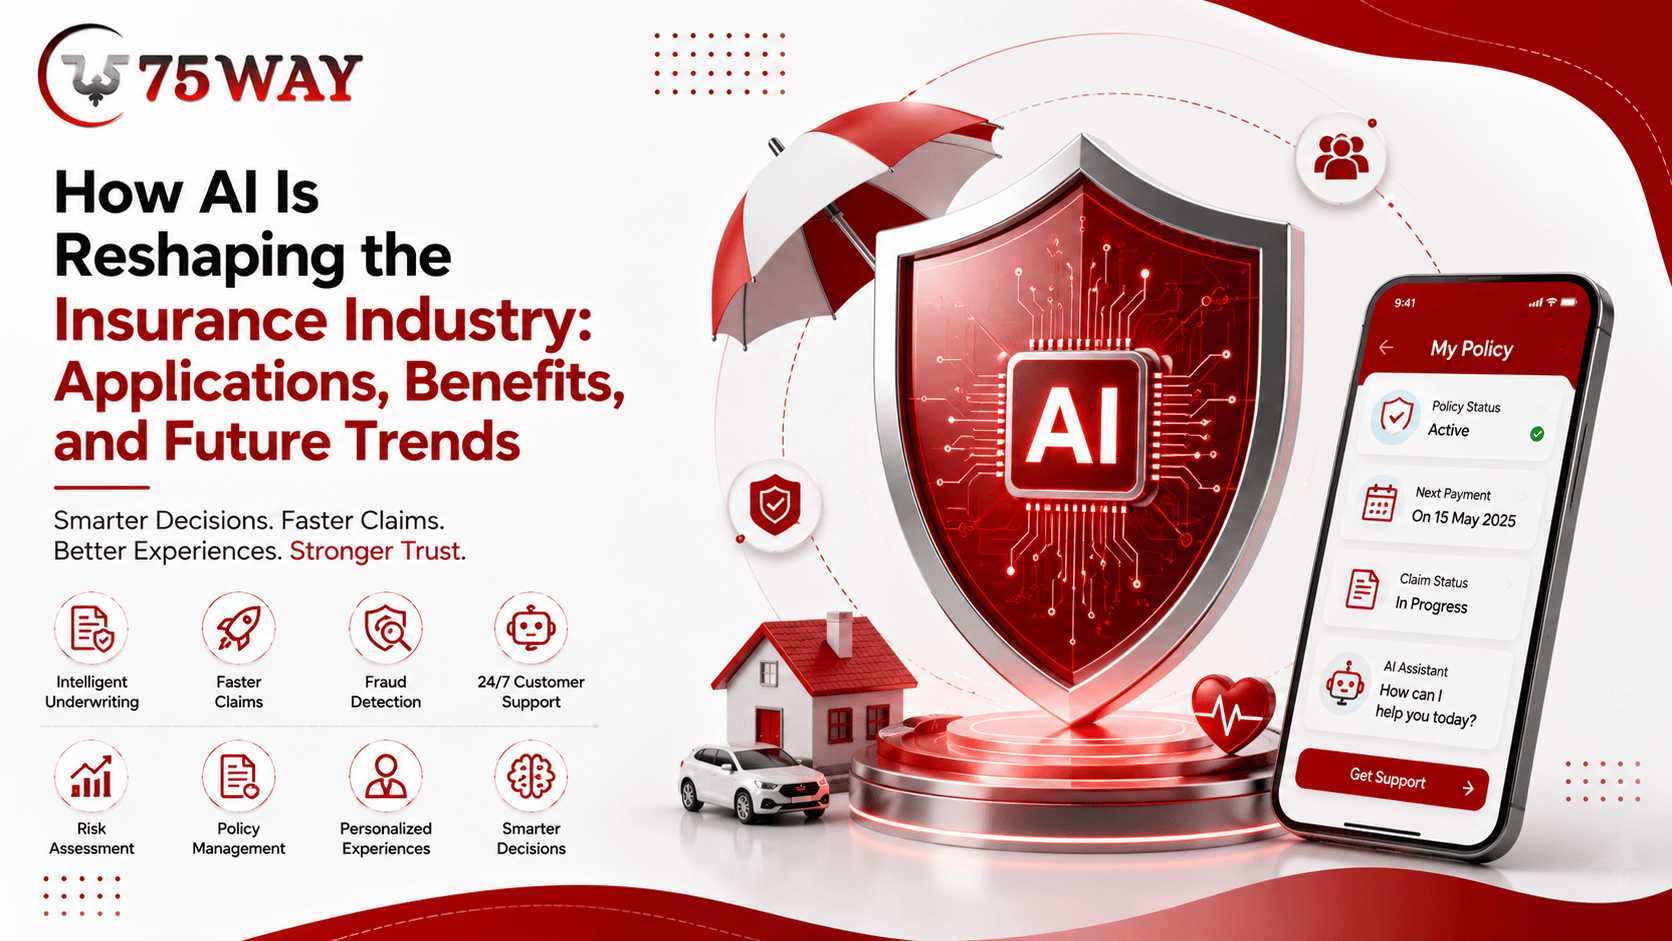
The insurance industry is undergoing a major digital transformation as insurers look for faster, more accurate, and customer-focused ways to manage policies, claims, risk, and service operations. AI solutions for insurance companies are helping organizations analyze large volumes of information, automate repetitive workflows, identify unusual patterns, and provide more responsive customer experiences. From underwriting and fraud detection to claims processing and virtual assistance, artificial intelligence is becoming a practical tool across the insurance value chain.
However, adopting intelligent technology is not simply about adding automation to existing processes. Insurers need to identify suitable use cases, establish reliable data practices, maintain regulatory compliance, and ensure that automated decisions remain transparent and accountable. Understanding these factors can help insurance businesses adopt AI strategically rather than treating it as a short-term technology trend.
Insurance companies manage enormous amounts of structured and unstructured information.
This can include:
Analyzing this information manually can consume substantial time and resources.
Intelligent systems can process large datasets and identify patterns that may help insurance professionals make faster and more informed decisions. The technology can support employees rather than completely replacing human expertise.
For insurers, the greatest value often comes from combining machine intelligence with established business processes.
Underwriting is one of the areas where artificial intelligence can have a significant impact.
Traditional underwriting may involve reviewing numerous documents, customer details, historical records, and risk factors before determining policy terms.
Intelligent models can assist by analyzing relevant information and identifying patterns associated with different levels of risk.
Depending on the insurance category, systems may evaluate:
This can help underwriters prioritize cases and spend more time on complex situations.
The objective is not necessarily to remove human involvement. Instead, automated analysis can provide additional information that supports professional judgment.
Claims management can involve multiple stages, including submission, documentation, verification, assessment, approval, and settlement.
Manual processes can create delays when employees need to review large amounts of information individually.
AI-powered workflows can assist with tasks such as:
For example, an intelligent system may extract relevant information from uploaded documents and organize it for a claims professional.
This can reduce repetitive administrative work and potentially shorten processing times.
Fraud is a major concern for insurers because suspicious activity can increase financial losses and ultimately affect operational efficiency.
Machine learning can analyze large volumes of claims and identify unusual combinations of factors.
A fraud detection system may examine:
Rather than treating every claim equally, the system can assign risk scores or flag cases for additional investigation.
This allows specialist teams to focus their attention where it may be most valuable.
Importantly, a flagged claim should not automatically be treated as fraudulent. Human investigation and appropriate procedures remain important before making consequential decisions.
Risk assessment is fundamental to insurance.
Insurers need to estimate the probability and potential cost of future events when designing policies and determining appropriate terms.
Advanced analytics can analyze historical patterns alongside other relevant information to support risk evaluation.
For example, property insurers may analyze characteristics associated with environmental or structural risks, while vehicle insurers can evaluate driving-related information where legally and appropriately available.
The quality of the output depends heavily on the quality and relevance of the underlying data.
Customers increasingly expect services that reflect their individual circumstances.
AI can help insurers analyze customer behavior, preferences, policy history, and relevant risk information to support more personalized offerings.
Personalization may influence:
Instead of presenting identical offers to every customer, insurers can use analytics to understand different customer segments.
Personalization should still respect privacy requirements and avoid inappropriate use of sensitive information.
Insurance customers may need assistance outside traditional office hours.
Questions about policies, claims, payments, renewals, and documentation do not always occur during business hours.
This is where ai insurance solutions can support always-available digital service channels.
An intelligent assistant can potentially help customers:
Automated assistance should clearly distinguish between general information and situations requiring a qualified insurance professional.
Policy administration involves many repetitive activities.
These may include:
Automation can reduce the amount of manual effort required for routine operations.
For example, when a policy reaches a specific stage, the system can automatically trigger a notification or internal workflow.
This can improve consistency while freeing employees to focus on tasks requiring judgment and customer interaction.
Insurance businesses often handle extensive documentation.
Documents can arrive through emails, portals, uploads, scanned files, and other channels.
Natural language processing and document intelligence can help classify and extract information from these materials.
Potential applications include:
This can significantly reduce repetitive document-handling tasks.
Human review remains important for documents containing ambiguous or high-impact information.
Customer retention is an important business objective for insurance providers.
Predictive analytics can help organizations identify patterns associated with customer disengagement or potential policy cancellation.
Relevant signals may include:
Insurers can use these insights to develop more appropriate retention strategies.
Instead of sending the same communication to every customer, organizations can tailor outreach according to relevant customer needs and circumstances.
Pricing insurance products requires careful consideration of risk, market conditions, customer characteristics, and regulatory requirements.
Advanced analytics can help insurers understand patterns across historical and current datasets.
These insights can support pricing teams by highlighting:
However, automated pricing requires careful governance.
Models should be tested for accuracy, unintended discrimination, explainability, and compliance with applicable regulations.
Computer vision can help insurers analyze photographs associated with claims.
For example, in certain property or vehicle insurance workflows, customers may submit images showing damage.
An intelligent image-analysis system can potentially identify visible damage, categorize affected areas, and support preliminary assessment.
This can help claims teams process straightforward cases more efficiently.
The technology should be appropriately validated because image quality, lighting, angles, and other factors can affect automated analysis.
AI does not have to be customer-facing.
Internal teams can also benefit from intelligent tools.
Agents and employees may use AI-assisted systems to:
These capabilities can reduce the time employees spend searching for information.
The result can be a more productive workforce without removing the human relationship that remains important in insurance.
Customers often become frustrated when they do not know what is happening with a claim.
Automated communication can provide timely updates at different stages of the process.
Notifications may inform customers when:
Clear communication can reduce unnecessary support requests and improve transparency.
The messages should remain accurate and avoid making promises that the underlying system cannot guarantee.
Modern customers expect digital services to be available whenever they need them. ai solutions for 24/7 customer service in insurance can help insurers provide automated assistance beyond standard business hours.
An intelligent service layer can handle common requests continuously and route more complex cases to appropriate human representatives.
For example, a customer could ask about a claim at midnight and receive basic status information immediately.
This approach can improve accessibility without requiring customer-service teams to remain available for every routine question around the clock.
Insurance organizations make decisions across multiple departments.
Management may need to understand:
AI-powered analytics can consolidate information and identify patterns across these areas.
Dashboards can help decision-makers understand changing trends rather than relying exclusively on static reports.
Better visibility can support faster strategic responses.
Artificial intelligence depends heavily on reliable data.
If information is incomplete, inconsistent, outdated, or incorrectly labeled, model performance can suffer.
Insurance companies should establish processes for:
Organizations should also understand where their data originates and whether it can legally and ethically be used for a particular purpose.
A sophisticated model cannot compensate for fundamentally unreliable information.
Insurance companies manage sensitive customer information, making security a major consideration when implementing AI.
Systems may process personal details, financial information, policy records, claims documentation, and other sensitive data.
Organizations should consider:
Privacy requirements can vary according to geography, insurance category, and the nature of the information being processed.
Security should therefore be incorporated into the system architecture rather than added after development.
Insurance decisions can have significant financial consequences for customers.
This makes responsible AI governance particularly important.
Organizations should consider:
Employees and customers should receive appropriate explanations about automated processes where required.
Models should be evaluated for potential bias and unintended discriminatory outcomes.
Important decisions should have suitable human review mechanisms.
Organizations need clear ownership for monitoring and maintaining AI systems.
Performance should be continuously evaluated because data patterns can change over time.
Responsible governance can help insurers balance automation with fairness and customer trust.
Most insurers already operate multiple technology platforms.
These may include:
AI should ideally work with these systems rather than creating another isolated information environment.
APIs and integration layers can connect intelligent services with existing infrastructure.
This approach can help organizations introduce AI gradually without completely replacing established systems.
Insurance companies should not attempt to implement every possible AI capability simultaneously.
A better strategy is to identify areas where technology can create measurable value.
A business might start with:
Challenge: Claims employees spend too much time classifying documents.
Potential approach: Automated document classification and information extraction.
Or:
Challenge: Customers frequently ask basic policy questions outside business hours.
Potential approach: An intelligent customer-service assistant.
Starting with a focused problem makes it easier to establish goals and evaluate results.
Organizations should define performance indicators before launching an AI initiative.
Potential metrics include:
| Application Area | Possible Performance Metrics |
|---|---|
| Claims Automation | Processing time, resolution time |
| Fraud Detection | Detection rate, false-positive rate |
| Customer Service | Response time, resolution rate |
| Underwriting Support | Review time, decision efficiency |
| Document Processing | Processing speed, extraction accuracy |
| Customer Retention | Renewal rate, engagement |
| Risk Analytics | Prediction accuracy, portfolio performance |
The appropriate metric depends on the objective.
A customer-service assistant should not be judged using the same measurements as a fraud detection system.
Implementing artificial intelligence in insurance requires expertise across software engineering, data management, AI development, security, integration, and user experience.
75way Technologies can support organizations exploring intelligent insurance applications by helping translate business requirements into scalable digital solutions.
A suitable development partner should evaluate the insurer’s existing infrastructure, identify practical automation opportunities, plan integrations, establish security requirements, and create systems that can evolve as business needs change.
The focus should remain on measurable business outcomes rather than simply adding AI features.
Artificial intelligence offers significant potential, but insurers should also prepare for implementation challenges.
Information may be distributed across legacy systems and departments.
Older platforms may require additional work before they can communicate effectively with modern AI services.
Insurance is a highly regulated industry, and automated decision-making may require additional governance.
Stakeholders may need to understand how a system reached a particular recommendation or prediction.
Employees may require training to understand how intelligent tools fit into existing workflows.
Models need monitoring, evaluation, retraining, and updates as business conditions change.
Addressing these challenges early can improve implementation outcomes.
The role of artificial intelligence in insurance is likely to expand as organizations gain access to better data, stronger computing infrastructure, and increasingly capable models.
Future applications may include:
The next stage of insurance technology will likely involve connected systems where intelligence is integrated throughout the customer and operational journey.
However, the human role will remain important.
Insurance involves financial risk, customer trust, complex circumstances, and regulatory responsibilities. Technology should therefore augment professional expertise rather than remove accountability from important decisions.
Artificial intelligence is changing insurance by helping organizations process information faster, automate repetitive activities, improve customer service, strengthen risk analysis, and make more informed operational decisions.
From underwriting and claims management to fraud detection, document processing, personalization, and customer support, intelligent technologies can create opportunities across nearly every stage of the insurance lifecycle.
The key to successful adoption is choosing the right problems to solve.
Organizations should begin by identifying operational bottlenecks, customer frustrations, data opportunities, and measurable business objectives. They can then select appropriate technologies, establish governance processes, integrate existing systems, and continuously evaluate performance.
AI for insurance should not be viewed as a replacement for insurance expertise. Its greatest potential lies in giving professionals better information, reducing repetitive workloads, and creating faster and more convenient customer experiences.
As the industry continues to evolve, insurers that combine intelligent technology with strong data practices, responsible governance, and human oversight will be better positioned to build efficient and customer-focused operations.