Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Market Overview
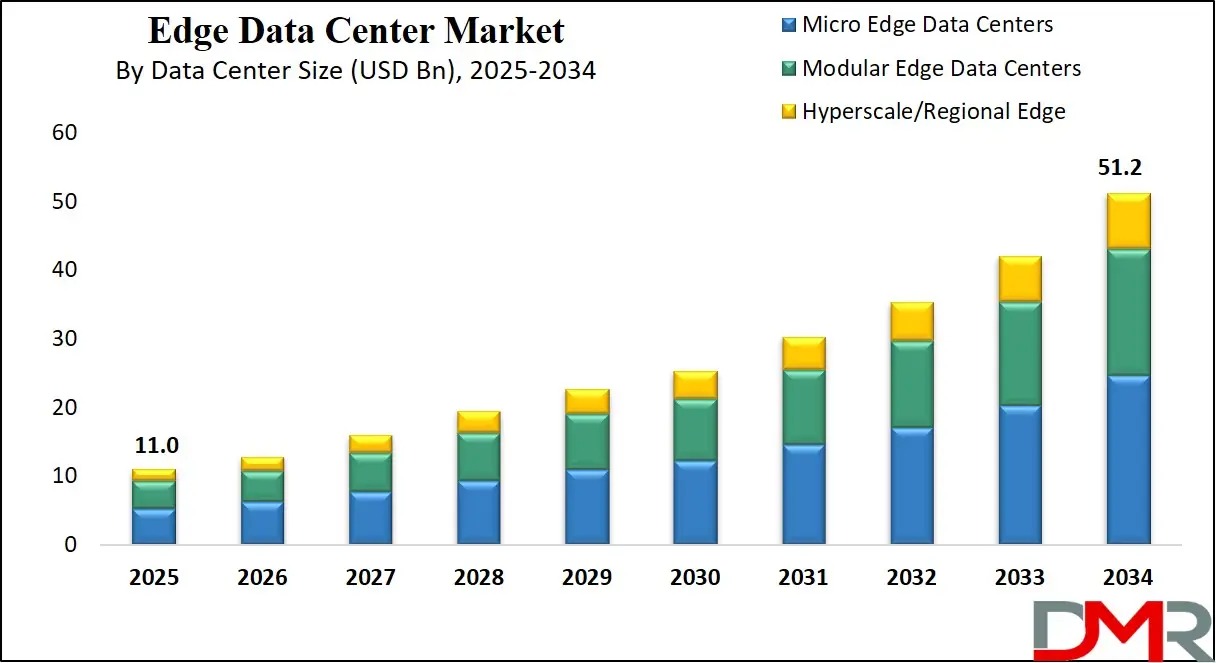
According to Dimension Market Research, the global Edge Data Center Market is projected to reach USD 11.0 billion in 2025 and is expected to grow to USD 51.2 billion by 2034, expanding at a CAGR of 18.7%. This growth is driven by rising demand for low-latency computing, IoT data processing, and decentralized infrastructure across 5G networks, AI workloads, and real-time analytics applications.
Edge data refers to the processing, collection, and analysis of data at or near the physical location where it is generated rather than relying on centralized cloud or data center environments. This approach significantly reduces latency, enhances response times, and improves bandwidth efficiency. Edge data systems are designed to support real-time applications by bringing computation closer to the source, whether it be sensors in a factory, autonomous vehicles, or mobile devices in remote areas. By minimizing the distance between the data source and the processing unit, edge data architecture enables faster decision-making, greater data privacy, and more resilient network infrastructure.
The global edge data center market is evolving rapidly as the demand for low-latency data processing and localized computing continues to grow. Enterprises across sectors such as telecommunications, manufacturing, healthcare, and retail are deploying edge facilities to handle massive volumes of data generated by IoT devices, AI applications, and smart systems. These compact and decentralized centers act as regional hubs that bridge the gap between end-users and core data centers, improving service delivery and enhancing real-time analytics capabilities. Advancements in edge hardware, energy-efficient cooling systems, and software-defined networking are further fueling the adoption of edge infrastructure.
This market is witnessing strategic expansions and collaborations among technology providers, telecom operators, and infrastructure companies aiming to build scalable edge ecosystems. Regions like North America and Asia-Pacific are experiencing significant growth due to investments in 5G networks, smart city projects, and autonomous systems. As data consumption surges and enterprises shift toward distributed computing models, the edge data center industry is positioned to play a foundational role in modern IT architecture. The integration of machine learning, containerization, and next-gen networking technologies like private 5G and Wi-Fi 6 is expected to create new use cases and drive sustained market momentum.
Definition and Market Significance
Edge data centers are compact, decentralized facilities located close to the source of data generation, designed to process, store, and analyze data locally rather than transmitting it to centralized cloud or hyperscale data centers. These facilities support latency-sensitive applications, reduce bandwidth consumption, and enable real-time decision-making across industries.
The importance of edge data centers lies in their ability to deliver ultra-low-latency computing, enhance data privacy, and improve network resilience. As IoT devices, autonomous systems, and AI workloads proliferate, edge data centers become essential for handling the massive volumes of data generated at the network edge while ensuring fast, reliable, and secure processing.
Edge data centers also support broader digital transformation objectives by enabling smart cities, industrial automation, telemedicine, immersive media, and autonomous transportation, positioning them as a foundational layer in modern distributed IT architectures.
Looking for Something Specific? Get Free Sample:
https://dimensionmarketresearch.com/request-sample/edge-data-center-market/
Market Drivers
A major factor driving the Edge Data Center Market is the surge in real-time data processing demand. The exponential rise of data-intensive applications, such as IoT ecosystems, autonomous systems, and augmented reality, has led to a growing need for real-time analytics and ultra-low-latency computing. Edge data centers enable localized data processing, reducing the reliance on centralized cloud networks and enhancing performance for latency-sensitive operations.
The expansion of 5G and next-gen network infrastructure is another key driver supporting market expansion. The global rollout of 5G networks is acting as a significant enabler for the edge data center market. 5G’s promise of high-speed, low-latency communication makes it ideal for distributed computing models. Telecom operators are deploying micro edge facilities to bring compute and storage closer to the network edge, improving user experience for applications such as mobile streaming, gaming, and real-time communication.
The growing adoption of edge computing across industries such as manufacturing, healthcare, retail, and transportation is also contributing to market growth, as organizations seek to enhance operational efficiency, reduce costs, and improve customer experiences.
Market Trends
The adoption of modular and prefabricated edge data centers is emerging as an important trend in the market. To accelerate deployment and reduce on-site construction complexity, organizations are turning to modular edge data center designs. These prefabricated units are compact, easily transportable, and scalable based on demand, making them ideal for remote or space-constrained locations. This trend is driving innovation in containerized infrastructure, integrated cooling systems, and plug-and-play deployment models.
Another significant trend is the focus on sustainable and energy-efficient infrastructure. As the edge data center footprint expands, energy consumption and environmental impact have become key concerns. Operators are adopting advanced cooling techniques, renewable power sources, and AI-based energy management systems to improve sustainability. Green edge data centers not only reduce operational costs but also align with global ESG goals, making energy efficiency a competitive differentiator in the market.
The growing integration of AI and machine learning at the edge is also transforming the market, enabling instant decision-making on-site without data needing to be transferred to centralized servers.
Market Restraints
Despite its strong growth potential, the Edge Data Center Market faces certain limitations. High capital investment and deployment costs pose significant challenges. Setting up edge data centers involves significant capital expenditure in physical infrastructure, power systems, cooling technologies, and localized hardware. Unlike centralized hyperscale data centers that benefit from economies of scale, edge facilities are smaller but distributed across multiple geographic locations, growing operational complexity and cost.
Limited standardization and interoperability is another significant restraint. The edge computing landscape is still evolving, with varying architectures, vendor-specific solutions, and a lack of universally accepted protocols. This lack of standardization poses integration challenges, especially when managing hybrid or multi-edge environments. Ensuring seamless data flow, consistent security policies, and device interoperability across multiple edge nodes continues to be a bottleneck for edge data center scalability and long-term sustainability.
In addition, the need for skilled personnel to manage distributed infrastructure and the complexity of integrating edge systems with existing IT environments can slow adoption.
Market Opportunities
The rising demand from emerging economies and smart cities presents significant growth opportunities. Developing regions in Asia-Pacific, Latin America, and the Middle East are rapidly investing in smart city infrastructure, connected transportation, and digital public services. These initiatives rely heavily on real-time data collection and processing, creating a strong use case for localized edge computing. Edge data centers can help manage urban data loads, improve public safety systems, and support applications like traffic optimization and waste management, offering immense growth potential in these emerging markets.
AI and machine learning integration at the edge is another promising opportunity. With advancements in edge AI chips and inference engines, there is a growing opportunity to embed artificial intelligence directly into edge data centers. This allows for instant decision-making on-site, without data needing to be transferred to centralized servers. Use cases include predictive maintenance in manufacturing, fraud detection in banking, and intelligent video analytics in surveillance. Edge AI is unlocking new business models and enhancing the value proposition of edge infrastructure across industries.
Furthermore, the expansion of edge-as-a-service models and the growth of colocation-based edge deployments are expected to open new opportunities for organizations of all sizes.
Segmentation
The Edge Data Center Market is categorized based on component, infrastructure, data center size, deployment mode, organization size, application, and end-user industry.
By component, the solutions segment is expected to lead the component category, accounting for approximately 63.0% of the total market share in 2025. This dominance is primarily driven by the growing demand for robust IT infrastructure, including servers, storage systems, power units, cooling solutions, and network connectivity equipment. Services, including deployment, consulting, integration, maintenance, and managed services, are also playing a critical role in the growth of the edge data center ecosystem.
By infrastructure, IT infrastructure is projected to remain the dominant category, capturing around 42.0% of the total market share in 2025. This is largely attributed to the growing need for high-performance computing, storage, and networking systems at the edge, where vast volumes of data are generated and need to be processed locally. Power and cooling systems form a vital part of the edge data center setup, ensuring uninterrupted operations and maintaining optimal performance of equipment.
By data center size, micro edge data centers are expected to maintain a strong lead, capturing 48.0% of the total market share in 2025. These compact, containerized facilities are designed to process data close to the source, making them ideal for supporting latency-sensitive applications such as IoT deployments, smart city infrastructure, autonomous vehicles, and remote industrial operations. Modular edge data centers are gaining significant traction due to their flexibility, scalability, and faster deployment capabilities.
By deployment mode, on-premise deployment is set to dominate, accounting for 44.0% of the total market share in 2025. This approach allows organizations to build and manage edge data centers within their own facilities, giving them complete control over infrastructure, security, compliance, and customization. Colocation is also playing a vital role in the growth of the edge data center ecosystem, offering scalable infrastructure, robust connectivity, and round-the-clock support.
By organization size, large enterprises are expected to lead, capturing 61.0% of the total market share in 2025. These organizations typically have complex IT infrastructures, high data processing needs, and operations spread across multiple geographic locations, all of which drive the demand for decentralized computing solutions. Small and medium-sized enterprises (SMEs) are also adopting edge data centers, albeit at a more gradual pace.
By application, content delivery and streaming applications are expected to hold the largest share, accounting for 22.0% of the total market value in 2025. This dominance is driven by the growing global consumption of high-definition video, live broadcasts, cloud gaming, and immersive media experiences. IoT and smart devices also represent a major application area within the edge data center landscape.
By end-user industry, the telecommunication industry is projected to maintain its dominant position, accounting for 26.0% of the total market share in 2025. This leadership is largely driven by the ongoing global rollout of 5G networks, the exponential increase in mobile data traffic, and the need for ultra-low latency services. The banking, financial services, and insurance (BFSI) sector is also leveraging edge data centers to enhance its digital infrastructure.
Regional Analysis
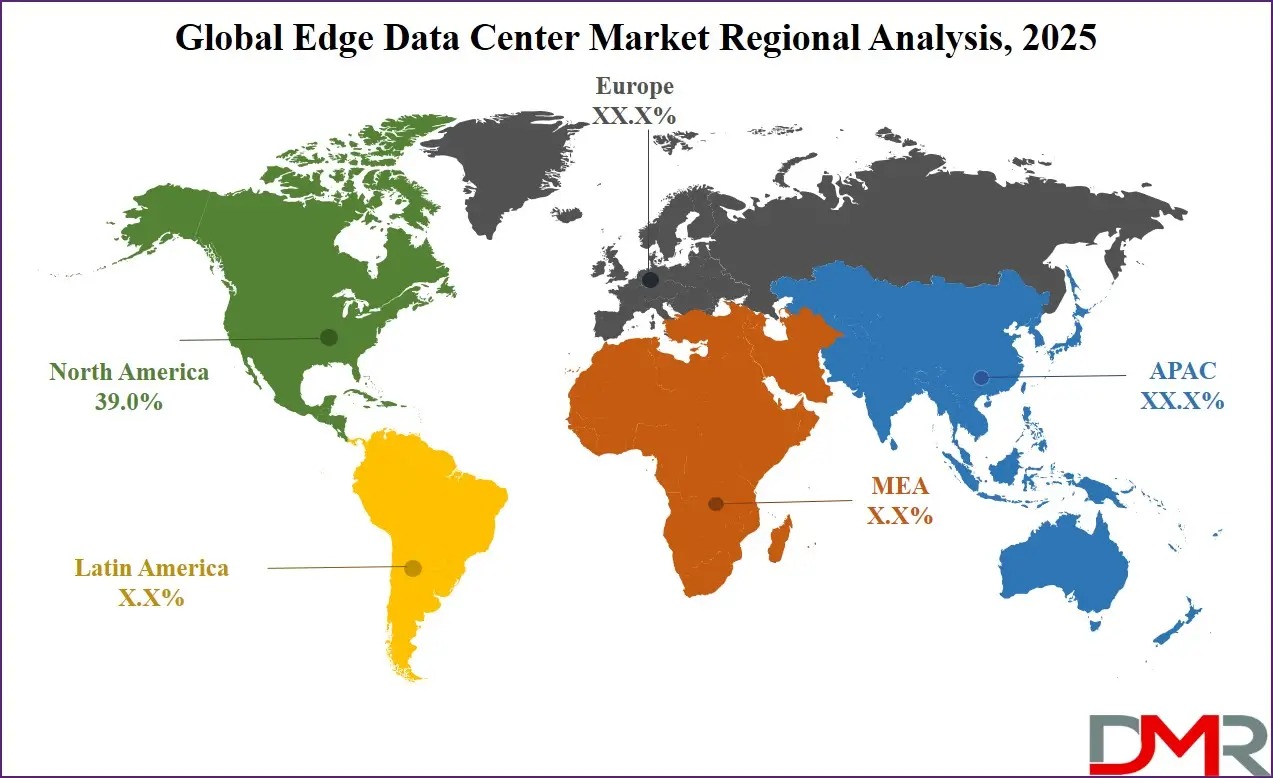
North America is projected to dominate the global edge data center services market in 2025, capturing 39.0% of the total market revenue. This leadership position is supported by the region’s advanced digital infrastructure, early adoption of emerging technologies, and strong presence of major cloud service providers, telecom operators, and data center vendors. The widespread deployment of 5G networks, integrated with high demand for low-latency applications such as autonomous vehicles, real-time analytics, and immersive media, is driving substantial investment in edge computing infrastructure. The US market is projected to be valued at USD 3.6 billion in 2025, reaching USD 15.4 billion in 2034 at a CAGR of 17.5%.
Europe holds a substantial share of the edge data center market, estimated to reach approximately USD 2.6 billion in 2025. This strong position is driven by the region’s mature digital ecosystem, robust connectivity infrastructure, and proactive investments in next-generation technologies. Key economies such as Germany, France, the UK, and the Netherlands are leading the charge with widespread 5G rollout, growing adoption of IoT devices, and growing reliance on real-time data processing across industries. The market is expected to grow at a CAGR of 17.1% from 2025 to 2034.
Asia Pacific is expected to witness the most significant growth in the edge data center market over the coming years, driven by rapid digital transformation, expanding internet penetration, and growing investments in smart city initiatives. Countries such as China, India, Japan, and South Korea are aggressively rolling out 5G infrastructure, supporting a surge in real-time applications across sectors like manufacturing, healthcare, retail, and transportation. Japan’s market is projected to reach approximately USD 515 million in 2025 at a CAGR of 16.2%.
Latin America and the Middle East & Africa are gradually adopting edge data center solutions as digital infrastructure improves and awareness of low-latency computing benefits grows, with Brazil, Mexico, the UAE, and Saudi Arabia emerging as key markets.
Competitive Landscape
The global competitive landscape of the edge data center market is characterized by a mix of established technology giants, telecom infrastructure providers, and emerging specialized players, all vying to capture market share through innovation, strategic partnerships, and geographic expansion. Companies like Schneider Electric, Vertiv, Dell Technologies, and HPE lead the market with comprehensive infrastructure solutions, while cloud service providers such as Amazon Web Services (AWS) and Microsoft Azure are investing in edge computing capabilities to extend their service reach. Telecom operators are also playing a crucial role by integrating edge facilities into their 5G networks to enhance data delivery and service performance.
Prominent players include Schneider Electric, Vertiv, Hewlett-Packard Enterprise (HPE), Dell Technologies, Huawei Technologies, Cisco Systems, IBM Corporation, NVIDIA Corporation, Eaton Corporation, Rittal GmbH & Co. KG, Equinix, Inc., EdgeConneX, Compass Datacenters, Vapor IO, Stack Infrastructure, Cyxtera Technologies, Zella DC, Iron Mountain Inc., AT&T Inc., and Amazon Web Services (AWS). Recent developments include Schneider Electric’s launch of AI-integrated EcoStruxure Micro Data Centers (June 2025), Vertiv’s introduction of the Edge Lithium-Ion UPS solution (April 2025), Equinix’s acquisition of a regional edge data center operator in Southeast Asia (March 2025), and EdgeConneX’s USD 300 million funding round (May 2025).
Technological Advancements
Rapid advancements in edge hardware, energy-efficient cooling systems, and software-defined networking are transforming the edge data center market. AI is profoundly transforming the market by enhancing operational efficiency, enabling intelligent data processing, and accelerating the adoption of next-gen applications. AI also enhances infrastructure management within edge data centers through predictive maintenance, intelligent power management, automated cooling systems, and workload optimization.
AI-driven monitoring tools can detect anomalies, anticipate hardware failures, and balance loads in real time, significantly improving uptime and energy efficiency. Additionally, AI supports advanced cybersecurity protocols by enabling edge facilities to detect and respond to threats instantaneously.
Consumer Adoption Patterns
Telecommunications, BFSI, retail and e-commerce, healthcare, manufacturing and industrial IoT, IT and cloud service providers, and media and entertainment are increasingly adopting edge data centers to support latency-sensitive applications, improve operational efficiency, and enhance customer experiences. The growing availability of modular, colocation-based, and edge-as-a-service models is making edge infrastructure more accessible to organizations of all sizes.
Regulatory Environment
Regulatory frameworks across different regions, including data privacy regulations such as GDPR, data residency requirements, and various national digital infrastructure strategies, significantly influence the edge data center market. Compliance with these regulations drives investment in localized edge infrastructure and shapes deployment strategies.
Market Challenges
The edge data center market faces challenges related to high capital investment and deployment costs, limited standardization and interoperability, skilled workforce shortages, and the complexity of managing distributed infrastructure. Additionally, ensuring security, compliance, and performance across multiple edge nodes remains an ongoing challenge.
Future Outlook
The future of the Edge Data Center Market remains exceptionally promising as demand for low-latency computing, IoT data processing, and decentralized infrastructure continues to grow. Increasing adoption of 5G, edge AI, modular and prefabricated data centers, and sustainable infrastructure, along with expansion into emerging markets and smart cities, are expected to drive strong market growth during the forecast period, with the market projected to reach USD 51.2 billion by 2034 at a CAGR of 18.7%.
FAQs
What is the expected size of the Edge Data Center Market in 2025?
The market is expected to reach USD 11.0 billion in 2025.
What is the projected market value by 2034?
The market is forecast to reach USD 51.2 billion by 2034.
What is the CAGR of the Edge Data Center Market?
The market is expected to grow at a CAGR of 18.7% during 2025–2034.
Which component segment dominates the market?
Solutions are anticipated to dominate with 63.0% share in 2025.
Which region leads the global edge data center market?
North America is projected to lead with 39.0% of total market revenue in 2025.
Summary of Key Insights
The global Edge Data Center Market is expected to grow from USD 11.0 billion in 2025 to USD 51.2 billion by 2034, recording a CAGR of 18.7% during the forecast period. Solutions lead the component segment with 63.0% share, while IT infrastructure dominates with 42.0% share. Micro edge data centers lead data center size with 48.0% share, on-premise deployment leads with 44.0% share, and large enterprises represent 61.0% of organization size share. Content delivery and streaming lead applications with 22.0% share, and telecommunications leads end-user industries with 26.0% share. North America holds the largest regional share with 39.0% of global revenue in 2025, while Asia Pacific is projected as the fastest-growing region. The US market is projected to reach USD 15.4 billion by 2034 at a CAGR of 17.5%.
Purchase the Full Report
https://dimensionmarketresearch.com/checkout/edge-data-center-market/