Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
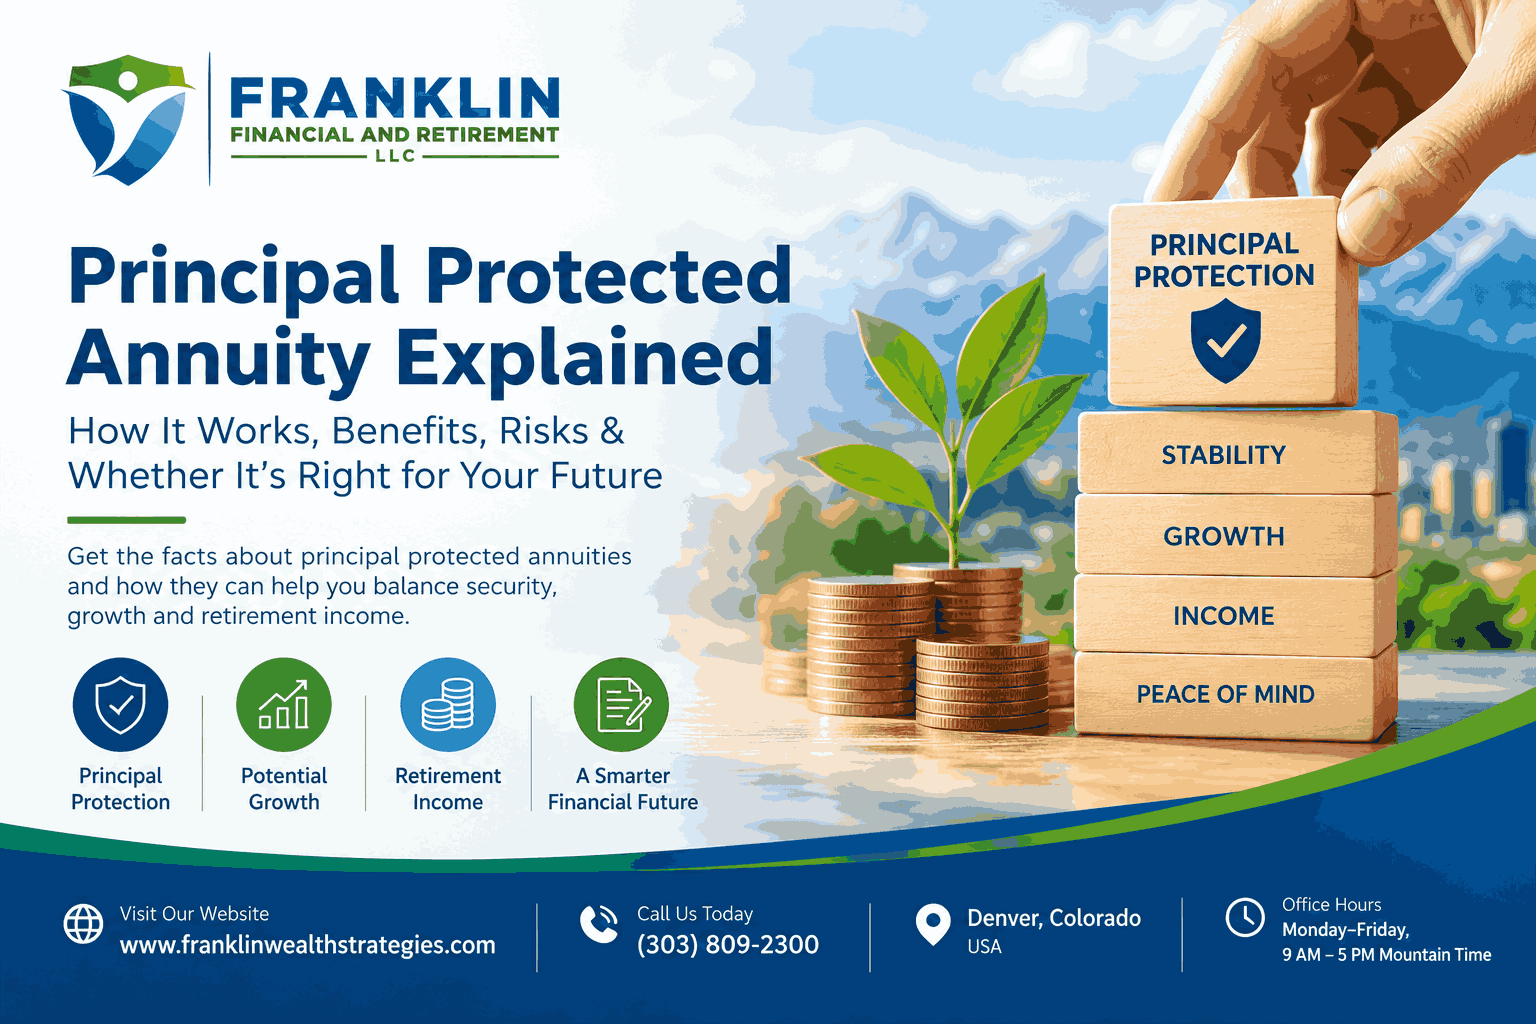
Imagine reaching retirement with a substantial portion of your savings intact, while still having an opportunity to earn interest. For people who want to reduce exposure to market losses without completely giving up growth potential, a principal-protected annuity can be an appealing option. But what exactly does it protect, and what trade-offs should you understand before purchasing one?
This principal protected annuity explained guide covers how these products work, their potential benefits and limitations, and what retirees should consider when evaluating whether an annuity belongs in their financial strategy.
A principal-protected annuity is an insurance-based financial product designed to provide a level of protection against certain market losses, depending on the specific contract. In exchange for an initial premium, the insurance company provides contractual guarantees and may offer interest-crediting opportunities.
The exact protection varies by product. Some annuities protect against losses in a particular market index while others provide protection at maturity or under specific contract conditions.
Because guarantees depend on the issuing insurance company’s financial strength and the terms of the contract, it is important to read the policy carefully rather than assuming that every annuity offers unlimited protection.
The basic concept is straightforward. You contribute money to the annuity, and the insurer credits interest according to the contract’s chosen strategy.
For example, suppose someone places $100,000 into an annuity with a defined principal-protection feature. If the linked index experiences a negative year, the contract may prevent that market decline from directly reducing the protected amount, subject to the contract’s terms.
However, protection does not necessarily mean your account can never lose value. Withdrawals, surrender charges, fees, income riders, market-value adjustments, or other contractual provisions can affect the amount available.
One of the key trade-offs is that greater protection can come with limitations on potential returns.
Depending on the product, interest may be calculated using features such as:
Fixed interest rates
Index-linked interest
Participation rates
Interest caps
Fixed spreads or margins
Contractual bonuses or riders
For this reason, investors should evaluate the entire contract rather than focusing only on the advertised protection feature.
For the right investor, a principal-protected annuity may provide several advantages.
Reduced exposure to market losses: Certain contracts can help protect against specified market declines.
Retirement income potential: Some annuities can be structured to provide income during retirement.
Tax-deferred growth: Depending on the account type and circumstances, earnings may grow tax-deferred until withdrawn.
Predictability: Contractual guarantees can provide greater certainty than directly investing in volatile assets.
Diversification: An annuity may complement other retirement assets rather than replacing an entire investment portfolio.
Protection comes with trade-offs, and understanding them is essential before making a decision.
First, annuities can have surrender periods, meaning withdrawing more than permitted during a certain period could result in surrender charges. Some contracts also have fees associated with optional benefits or riders.
Second, principal protection can limit growth. A market index might generate a strong return, but an annuity’s cap, participation rate, or other crediting formula may mean you receive only part of that performance.
Third, annuities can be complex. Contract terms, income options, withdrawal provisions, and crediting methods differ substantially between products.
Consider two hypothetical retirees, each investing $100,000. One chooses a product emphasizing guarantees and predictable income, while another chooses a market-linked strategy with greater upside potential.
The first retiree may value stability more than maximum growth. The second may have a longer investment horizon and greater tolerance for market fluctuations.
Neither approach is automatically better. The appropriate choice depends on income needs, financial objectives, time horizon, liquidity requirements, and risk tolerance.
A principal-protected annuity may be worth researching for individuals who:
Are approaching or already in retirement
Want to reduce exposure to market volatility
Value predictable retirement income
Have other liquid assets available for emergencies
Understand the product’s surrender and withdrawal rules
Want to complement, rather than replace, their broader retirement portfolio
It may be less suitable for someone who needs unrestricted access to their money or is primarily seeking maximum market growth.
Before purchasing an annuity, consider asking:
What exactly is protected?
How long does the protection apply?
What happens if I withdraw money early?
Are there surrender charges or other fees?
How is interest calculated?
Is there a cap or participation rate?
What income options are available?
What is the financial strength of the issuing insurer?
How does this product fit with my overall retirement plan?
A financial professional can help compare these details with other retirement-income strategies.
Understanding a principal protected annuity explained is about more than knowing that an annuity can provide protection. You need to understand exactly what is guaranteed, how interest is credited, what limitations apply, and how the product fits into your complete retirement strategy.
For retirees seeking a balance between protection, growth potential, and reliable income, an annuity may be worth evaluating—but it should be considered as part of a personalized financial plan.
If you’re exploring retirement-income strategies, visit Franklin Wealth Strategies at https://franklinwealthstrategies.com/ to learn more and discuss your financial goals with a professional.