Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
The semiconductor and electronics industries are becoming more complex as artificial intelligence (AI), electric vehicles, 5G, advanced computing, and connected devices expand. This growing complexity is increasing the need for accurate, high-speed, and repeatable testing throughout the electronics manufacturing process. The Automated Test Equipment Market is therefore gaining importance as manufacturers seek to identify defects, verify device performance, and improve production efficiency.
Automated Test Equipment (ATE) refers to computer-controlled systems that automatically evaluate electronic components, integrated circuits, printed circuit boards, and other devices. Modern ATE platforms combine hardware, software, data analytics, and automation to perform testing at high volumes while reducing manual intervention.
The Automated Test Equipment Market serves semiconductor manufacturers, electronics companies, automotive suppliers, telecommunications firms, aerospace and defense organizations, and other technology-intensive industries.
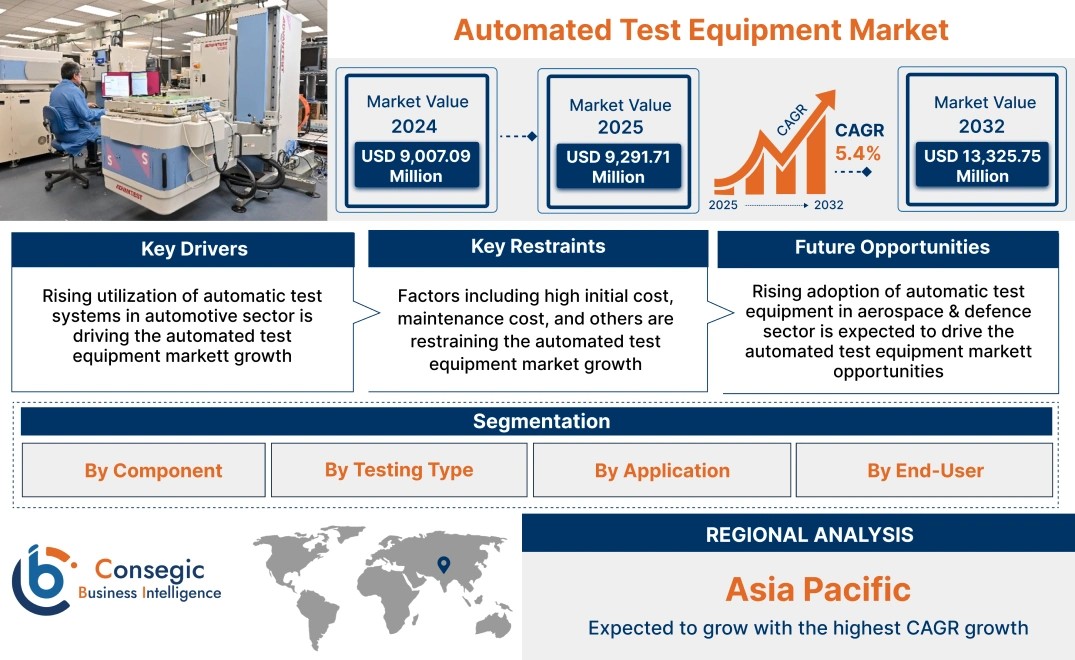
Automated Test Equipment Market size is estimated to reach over USD 13,325.75 Million by 2032 from a value of USD 9,007.09 Million in 2024 and is projected to grow by USD 9,291.71 Million in 2025, growing at a CAGR of 5.4% from 2025 to 2032.
Key ATE applications include:
The growing number of electronic components per vehicle, smartphone, industrial machine, and data center is creating additional testing requirements.
One of the strongest drivers is the rising complexity of semiconductor devices. Smaller process nodes, advanced packaging, chiplets, high-bandwidth memory, and increasingly integrated SoCs require more sophisticated testing procedures.
AI is another important factor. Gartner reported that worldwide semiconductor revenue reached USD 793 billion in 2025, up 21% year over year, while AI processing semiconductor revenue exceeded USD 200 billion.
Other major growth factors include:
Automotive electrification is particularly important because EVs contain substantial semiconductor content across battery-management systems, power electronics, sensors, infotainment, and advanced driver-assistance systems.
The integration of Artificial Intelligence and Machine Learning is changing how testing systems analyze large volumes of production data. AI-based systems can help identify abnormal patterns, detect potential defects, and optimize test sequences.
Digital transformation is also connecting ATE systems with manufacturing execution systems, cloud platforms, and centralized data environments. This allows manufacturers to track test results and identify recurring production problems.
Other emerging trends include:
Industry 4.0 is encouraging manufacturers to connect testing equipment with broader factory automation systems. This creates a more integrated production environment in which testing becomes part of continuous quality monitoring rather than an isolated final-stage activity.
Modern ATE systems combine test instruments, handlers, probers, industrial computers, software, interfaces, and measurement technologies. Depending on the application, equipment may perform digital, analog, mixed-signal, RF, power, memory, or functional testing.
The semiconductor industry is also increasing its focus on advanced testing as chip architectures evolve. The semiconductor test equipment market is projected by Fortune Business Insights to grow from USD 7.65 billion in 2025 to USD 14.38 billion by 2034, with ATE representing an important product category.
Advanced ATE development is focused on:
Advanced materials and manufacturing technologies are also influencing electronics production, increasing the need for specialized test methods.
North America benefits from strong semiconductor research, aerospace and defense activity, automotive technology development, and AI infrastructure investment. Demand for advanced testing solutions is supported by semiconductor manufacturing expansion and high-value electronics production.
Europe’s automotive industry is an important source of ATE demand. The growth of EVs, automotive electronics, industrial automation, and power semiconductors is creating additional testing requirements. Investment in semiconductor resilience and advanced manufacturing is also supporting the market.
Asia-Pacific remains the leading regional market because of its extensive semiconductor and electronics manufacturing ecosystem. Fortune Business Insights estimates that Asia-Pacific represented 50.70% of the global ATE market in 2025.
China, Taiwan, South Korea, Japan, Singapore, and other Asian economies are important manufacturing and testing centers.
Growing electronics manufacturing, automotive production, telecommunications infrastructure, and industrial modernization could create new opportunities for ATE suppliers.
Demand is emerging through telecommunications, industrial automation, energy infrastructure, defense electronics, and technology diversification. Investment in digital infrastructure could gradually support ATE adoption.
Investment opportunities are expanding across both hardware and software components of automated testing.
High-potential areas include:
Non-memory ATE remains particularly important. Grand View Research reports that the non-memory segment accounted for 57.5% of market revenue in 2025, supported by demand for logic ICs, SoCs, microcontrollers, analog devices, and automotive semiconductors.
Competition is centered on test accuracy, throughput, flexibility, software capabilities, and the ability to support emerging semiconductor architectures. Companies are investing in new product platforms, software-defined testing, advanced measurement technologies, partnerships, and research programs.
The competitive environment also includes collaborations between ATE manufacturers, semiconductor foundries, integrated device manufacturers, OSAT companies, automotive electronics suppliers, and research institutions.
Automation, robotics, data analytics, and AI are becoming important differentiators because manufacturers increasingly seek to reduce test time while maintaining reliability.
The Automated Test Equipment Market is expected to remain closely connected to semiconductor innovation through 2034. AI processors, chiplets, advanced packaging, automotive electronics, high-bandwidth memory, 5G infrastructure, and power semiconductors will continue creating new testing requirements.
The next generation of ATE will likely rely more heavily on AI, Machine Learning, cloud technologies, predictive maintenance, data analytics, IoT integration, and robotics. Smart Manufacturing can enable test equipment to communicate directly with production systems and automatically adjust workflows based on real-time information.
Sustainability will also become more relevant. Energy-efficient equipment, longer equipment lifecycles, software optimization, reduced manufacturing waste, and circular economy practices can help lower the environmental impact of electronics testing.
Overall, continued semiconductor complexity, rising electronic content, and increasing quality requirements should support long-term opportunities. However, high equipment costs, complex test-program development, and rapidly changing semiconductor architectures remain important challenges for manufacturers and ATE providers.
The Automated Test Equipment Market covers systems used to automatically test semiconductor devices, integrated circuits, electronic components, PCBs, and other electronic products. ATE improves testing speed, accuracy, consistency, and production efficiency while reducing dependence on manual inspection.
Major drivers include semiconductor miniaturization, AI chip development, electric vehicle adoption, 5G deployment, advanced packaging, growing electronics production, and increasing quality requirements. The rising complexity of integrated circuits is particularly important because advanced devices require more comprehensive testing.
Asia-Pacific is currently the leading region in several market assessments because of its large semiconductor and electronics manufacturing ecosystem. China, Taiwan, South Korea, and Japan have major semiconductor production and testing capabilities, supporting strong regional demand for automated test systems.
Major trends include AI-powered test analytics, Machine Learning, software-defined testing, cloud connectivity, predictive maintenance, IoT integration, robotics, parallel testing, and automated test-program optimization. These technologies are helping manufacturers improve throughput while managing increasingly complex semiconductor and electronic devices.
Opportunities are expected in AI semiconductor testing, automotive electronics, EV power systems, high-bandwidth memory, advanced packaging, RF devices, power semiconductors, and smart manufacturing. AI-enabled analytics and cloud-connected testing platforms are also likely to become increasingly important.
About Us
At Consegic Business Intelligence Pvt. Ltd., we empower organizations with actionable market intelligence, strategic insights, and data-driven research solutions that support informed business decision-making. Our comprehensive market research reports provide in-depth analysis of industry trends, competitive landscapes, emerging opportunities, and future growth prospects across diverse sectors.
Contact Us
Consegic Business Intelligence Pvt. Ltd.
Website: www.consegicbusinessintelligence.com
Email: sales@consegicbusinessintelligence.com
Phone: +1-833-313-3130