Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
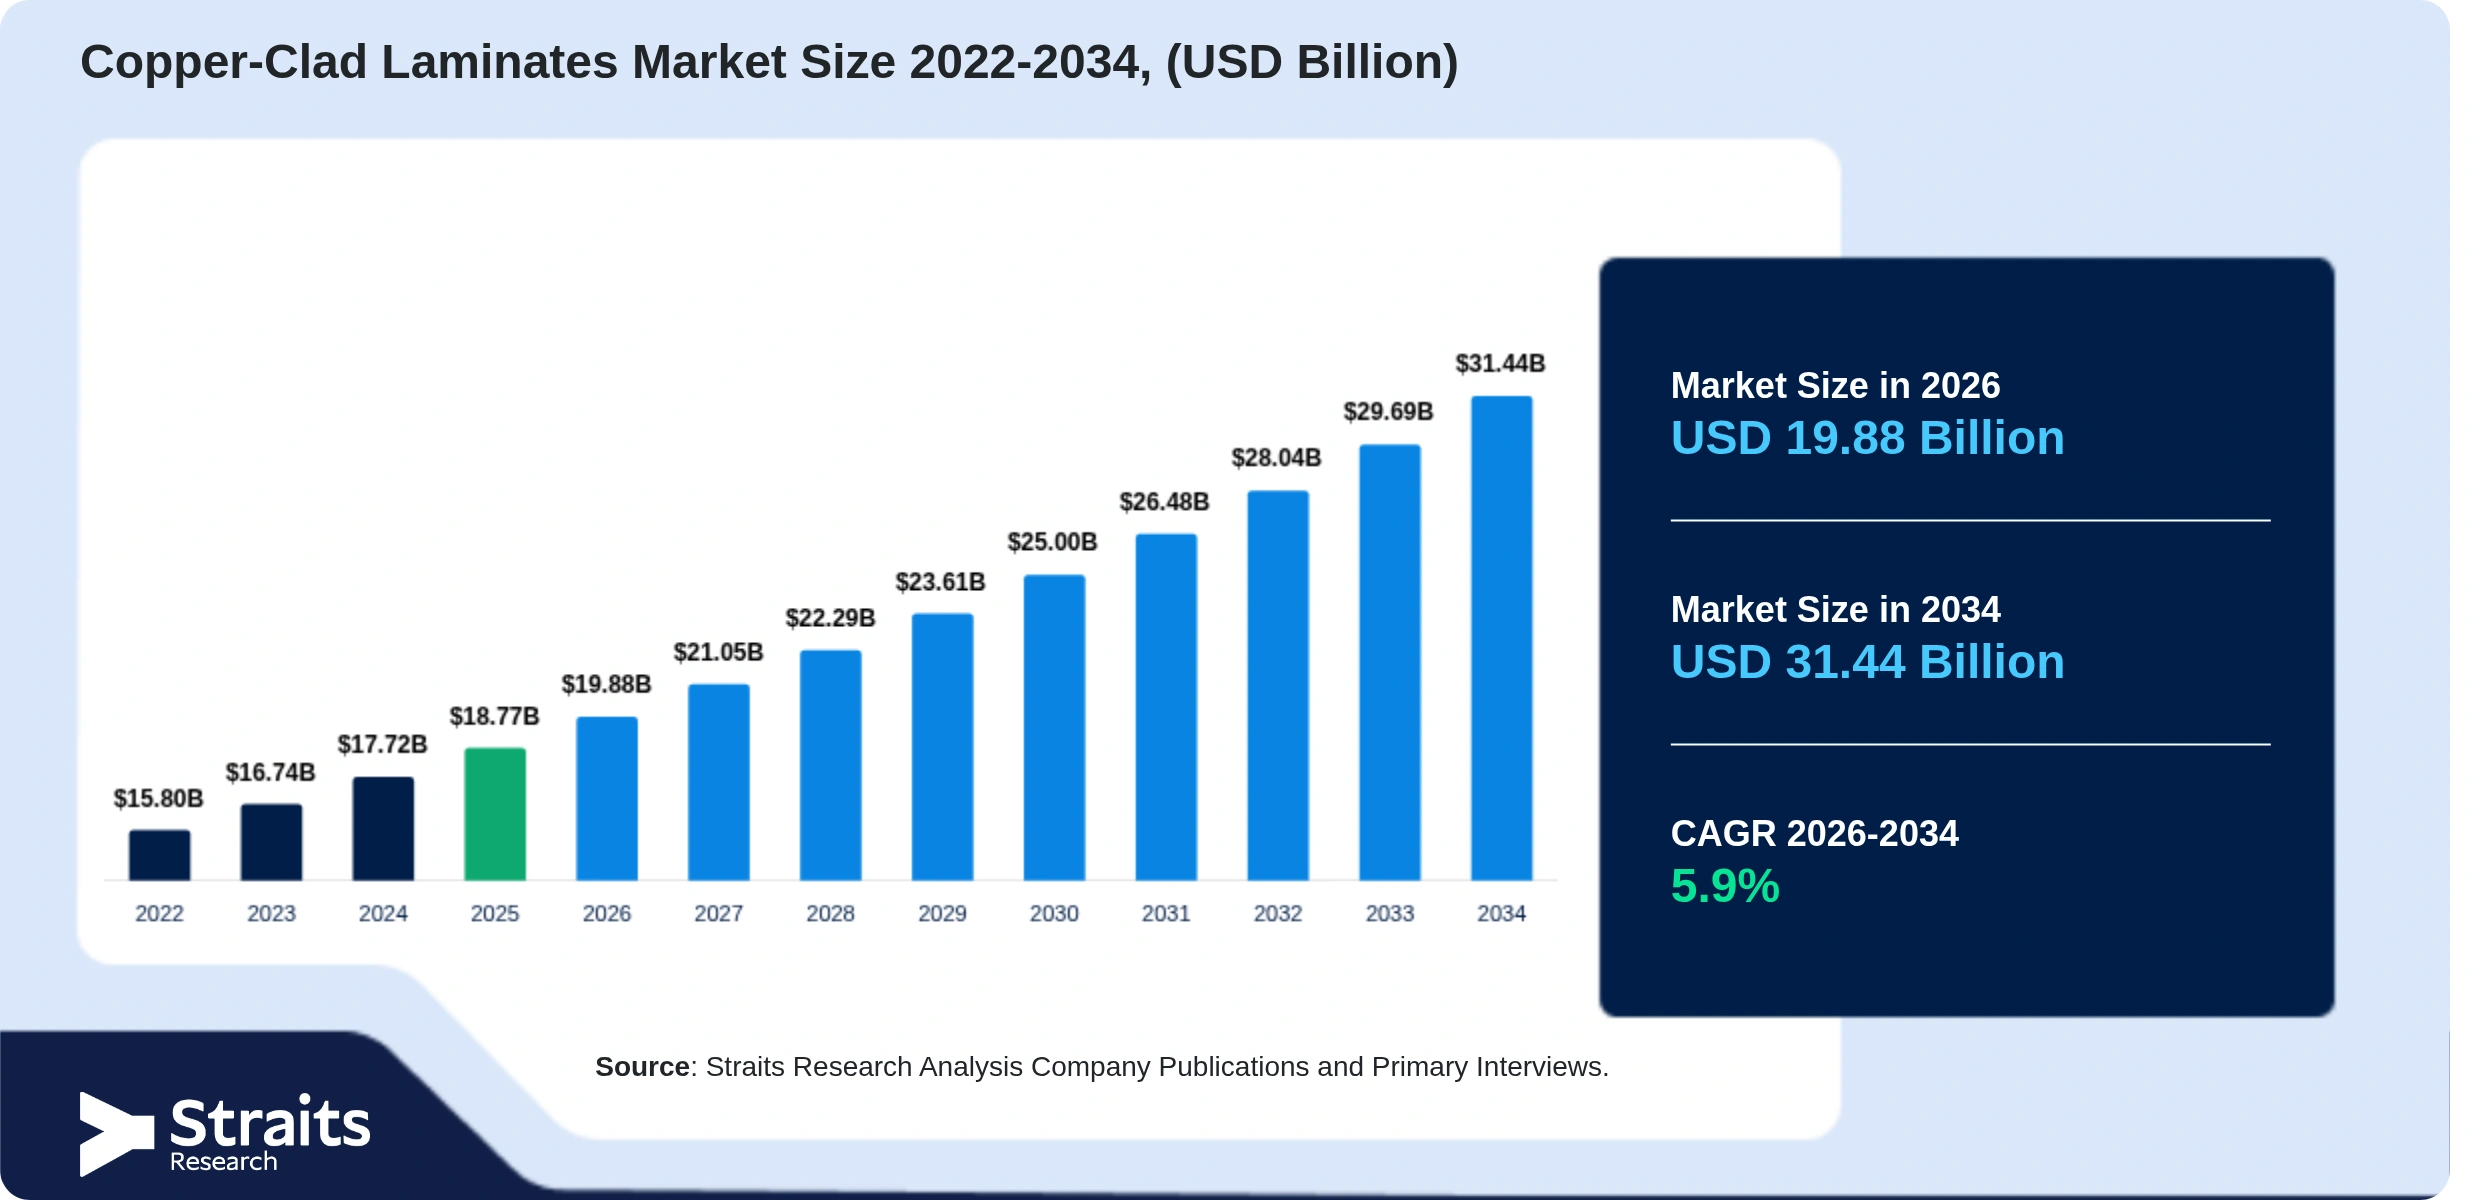
The global copper-clad laminates market was valued at USD 18.77 billion in 2025 and is projected to grow from USD 19.88 billion in 2026 to USD 31.44 billion by 2034, registering a CAGR of 5.9% during the forecast period 2026–2034. Copper-clad laminates (CCLs) are essential materials used in printed circuit board (PCB) manufacturing, combining copper foil with an insulating substrate, typically fiberglass or composite epoxy resin. The copper layer provides conductive pathways for electrical signals, while the substrate delivers mechanical support and electrical insulation. Their performance directly influences the reliability, signal integrity, and durability of electronic devices.
The market outlook reflects the expanding role of electronic components in telecommunications, computing, consumer devices, and automotive systems. As equipment becomes more compact and processes require faster data transmission, manufacturers are seeking laminates with improved thermal stability, electrical performance, and dimensional consistency. These requirements are supporting demand for conventional materials as well as specialized laminates designed for high-frequency and high-speed applications.
The growing use of advanced electronics is driving the copper-clad laminates market growth by increasing demand for reliable, high-performance PCBs. Telecommunications equipment, computing devices, and connected systems require circuit materials that maintain electrical insulation and signal quality under demanding operating conditions. Meanwhile, vehicle electrification is increasing the use of electronic control units, advanced driver-assistance systems (ADAS), radar sensors, and power electronics. These applications create demand for laminates with strong thermal resistance, mechanical stability, and consistent electrical properties, supporting market expansion across multiple industries.
Copper foil, glass fiber, epoxy resin, and other specialized inputs expose laminate producers to fluctuations in commodity prices and supply conditions. Rising procurement costs can increase manufacturing expenses and compress margins, particularly when customers resist price adjustments. Environmental requirements concerning chemical handling, emissions, waste management, and restricted substances also create compliance obligations. Manufacturers must balance cost efficiency with product quality and regulatory requirements, making raw material sourcing and production optimization important considerations within the market landscape.
Demand for advanced PCBs is creating opportunities for manufacturers to develop specialized copper-clad laminates for telecommunications, computing, and automotive electronics. Materials with improved thermal resistance, electrical insulation, and dimensional stability can support compact devices and increasingly dense circuit designs. The expansion of electric vehicles, ADAS technologies, and high-frequency communication systems further strengthens this opportunity. Suppliers capable of delivering reliable, application-specific materials can improve their competitive position and address emerging requirements across the market ecosystem.
The growing complexity of AI servers, high-performance computing systems, and data-center networks is increasing demand for copper-clad laminates with low dielectric loss and reliable signal transmission. This shift is encouraging material manufacturers to develop advanced resin systems and high-speed laminates that support dense, multilayer PCBs. The resulting emphasis on electrical performance and thermal stability is expanding the role of specialized materials in next-generation computing infrastructure.
The expansion of high-frequency communication networks and advanced driver-assistance systems is strengthening demand for laminates with stable dielectric properties and minimal signal attenuation. Manufacturers are refining material compositions to support millimeter-wave radar, wireless communication equipment, and other demanding electronic systems. These market trends are creating opportunities for differentiated products that address the performance requirements of high-frequency applications.
The copper-clad laminates market is segmented by product, type, reinforcement fiber, resin, application, and end user.
By product, FR-4 accounted for a share of 42.6% in 2025, owing to its cost-effectiveness, electrical insulation properties, and widespread use in PCB manufacturing. The halogen-free board segment is projected to register a CAGR of 6.8% during the forecast period, supported by demand for materials with reduced hazardous substances.
By type, rigid laminates remain important for durable circuit boards used in computers, industrial equipment, and consumer electronics, while flexible laminates are expected to grow at a CAGR of 6.6%. Demand for lightweight and bendable circuits across compact electronics and automotive systems supports flexible material adoption.
By reinforcement fiber, the glass fiber base segment accounted for 64.7% of the market in 2025, supported by its mechanical strength, dimensional stability, and suitability for large-scale PCB manufacturing. By resin, epoxy led with a 47.9% share in 2025, owing to its strong adhesion and established role in circuit board production. Polyimide is expected to grow at a CAGR of 6.8%, supported by its high-temperature resistance and suitability for flexible circuits.
By application, communication systems accounted for 29.4% in 2025, reflecting extensive use in telecommunications equipment and networking hardware. Vehicle electronics is projected to grow at a CAGR of 6.9%, driven by electrification and advanced driver-assistance technologies. By end user, consumer electronics held a 36.7% share in 2025, while the automotive segment is expected to grow at a CAGR of 6.8% as electronic content per vehicle increases.
Asia-Pacific dominated the market with a 48.6% share in 2025, supported by its extensive electronics manufacturing base and PCB production capacity. China benefits from large-scale manufacturing of consumer electronics, telecommunications equipment, computing systems, and electric vehicle components. Japan’s advanced materials industry and established electronics supply chain support demand for high-performance laminates, while India’s expanding electronics manufacturing and semiconductor-related capabilities offer additional growth potential.
North America is projected to register the fastest regional growth, with a CAGR of 6.7% during 2026–2034. Demand from data infrastructure, advanced computing, telecommunications, and aerospace and defense electronics supports the regional outlook. Investments in semiconductor manufacturing and AI-related infrastructure are also strengthening requirements for high-performance PCBs.
Europe accounted for 18.1% of the market in 2025, supported by demand from automotive electronics, industrial automation, telecommunications, and specialized electronic equipment. Germany’s automotive manufacturing and engineering industries provide an important demand base as vehicles incorporate more electronic control systems, driver-assistance technologies, and power-management components.
The copper-clad laminates competitive landscape includes large-scale manufacturers, specialty electronic materials producers, and suppliers of advanced circuit board materials. Key companies include Kingboard Holdings Ltd., Shengyi Technology Co., Ltd., ITEQ Corporation, Panasonic Corporation, Isola Group, Nan Ya Plastics Corporation, Doosan Corporation, and Taiwan Elite Material Co., Ltd. Competition centers on manufacturing scale, material performance, production efficiency, research and development, and specialized low-loss laminate technologies.
The source report identifies developments involving Shengyi Technology in April 2026 and Panasonic Industry in February 2026, associated with advanced low-loss, high-frequency, and thermally stable laminate materials. These developments reflect the industry’s focus on improving signal integrity and supporting demanding computing, telecommunications, automotive, and electronic applications.
Straits Research – Copper-Clad Laminates Market
Straits Research provides market intelligence, industry analysis, and strategic insights to help businesses understand market dynamics, evaluate opportunities, and make informed decisions.
For further information, customized research, or report inquiries, visit Straits Research or contact its research team.