Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
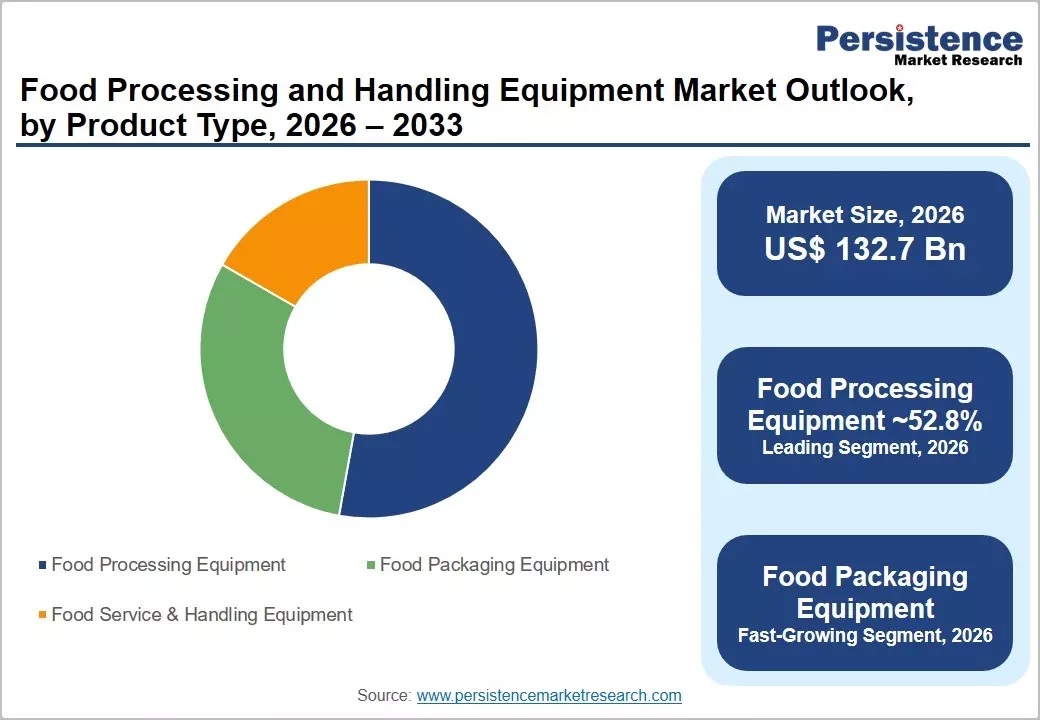
The global food processing and handling equipment market is expanding steadily as food manufacturers invest in automation, production efficiency, hygiene, and advanced processing technologies. The market is anticipated to be valued at US$ 132.7 Bn in 2026 and is projected to reach US$ 200.9 Bn by 2033, growing at a CAGR of 6.1% between 2026 and 2033. Rising global food consumption, growth of packaged and convenience foods, expanding processing capacity, and stricter food safety requirements are encouraging manufacturers to modernize production facilities. Demand for automated food processing equipment is also increasing as producers seek consistent product quality, higher throughput, reduced manual handling, and better control over operating costs.
Processing equipment represents an important component of the industry because manufacturers require reliable systems for mixing, cutting, grinding, cooking, forming, filling, packaging, and other production processes. Meat, dairy, bakery, beverage, processed food, and convenience food manufacturers are major equipment users. Geographically, Asia Pacific is an important growth market, supported by population growth, urbanization, expanding food manufacturing capacity, changing diets, and increasing consumption of packaged foods. Manufacturers across the food processing machinery industry are consequently investing in automation, hygienic equipment design, intelligent monitoring, energy efficiency, and flexible production systems.
𝐅𝐫𝐞𝐞 𝐒𝐚𝐦𝐩𝐥𝐞 & 𝐂𝐡𝐞𝐜𝐤 𝐭𝐡𝐞 𝐋𝐚𝐭𝐞𝐬𝐭 𝐌𝐚𝐫𝐤𝐞𝐭 𝐀𝐧𝐚𝐥𝐲𝐬𝐢𝐬:https://www.persistencemarketresearch.com/samples/3550
Key Highlights from the Report
Food Processing and Handling Equipment Market Segmentation
The food processing and handling equipment market can be segmented according to equipment type, application, level of automation, and end-use requirements. Processing machinery includes equipment designed for cutting, grinding, mixing, blending, forming, cooking, heating, cooling, and other operations that transform raw ingredients into finished or semi-finished food products. Handling equipment supports movement, sorting, conveying, storage, filling, and transportation of ingredients and finished products throughout production facilities.
Packaging and preparation systems are becoming increasingly integrated with processing lines as food manufacturers seek continuous and automated production environments. Equipment capable of handling multiple product formats provides manufacturers with flexibility when introducing new recipes, package sizes, or product varieties. Automated systems are particularly attractive to large-scale manufacturers because they can improve repeatability while reducing dependence on manual processes.
By application, demand extends across bakery and confectionery, dairy products, meat and poultry, seafood, beverages, fruits and vegetables, convenience foods, and other processed food categories. Each application has distinct requirements related to temperature, hygiene, material handling, processing speed, equipment configuration, and cleaning procedures. As product portfolios become more diversified, flexible machinery capable of rapid production changes is gaining importance.
Regional Insights
Asia Pacific is emerging as a prominent market for food processing equipment as food manufacturers increase capacity to serve growing populations and expanding urban markets. Rising disposable incomes and changing lifestyles are encouraging greater consumption of packaged foods, beverages, dairy products, bakery products, meat products, and ready-to-eat meals. Investments in modern food factories are subsequently generating demand for automated processing and material handling equipment.
North America maintains substantial demand for advanced food manufacturing technologies because of its mature processed-food sector and strong emphasis on automation, productivity, traceability, and food safety. Manufacturers increasingly seek equipment capable of improving operational visibility while reducing production downtime and labor-intensive processes. Replacement of aging machinery also supports equipment demand.
Europe remains an important market for hygienic and energy-efficient food processing machinery. Sustainability initiatives, strict safety standards, waste reduction objectives, and demand for efficient manufacturing systems are shaping purchasing decisions. Latin America, the Middle East, and Africa also present opportunities as food processing capacity develops alongside urbanization, retail expansion, cold-chain investment, and packaged-food consumption.
Market Drivers
Rising global food demand represents a fundamental growth driver for the food processing and handling equipment market. Population expansion, urban lifestyles, increasing household incomes, and evolving dietary preferences are contributing to higher consumption of processed and packaged food products. Food manufacturers must consequently increase production capacity while maintaining consistency, hygiene, and efficiency.
Automation provides another significant growth catalyst. Automated food processing equipment can improve production speed, reduce repetitive manual tasks, maintain standardized output, and enhance process control. Sensors, digital controls, robotics, machine vision, and connected manufacturing technologies are increasingly being integrated into processing facilities. These technologies can also provide production data that enables operators to identify inefficiencies and maintenance requirements.
Food safety requirements further encourage equipment modernization. Manufacturers need machinery designed for effective cleaning, contamination prevention, accurate temperature management, and hygienic material handling. Equipment constructed around sanitary design principles can help producers manage contamination risks while maintaining efficient manufacturing operations.
Market Restraints
High initial investment remains an important challenge, particularly for small and medium-sized food manufacturers. Advanced processing lines can require substantial expenditure on machinery, installation, facility modification, software integration, employee training, and ongoing maintenance. Companies operating with limited capital may therefore delay large automation projects or modernize production facilities gradually.
Maintenance complexity can create additional challenges. Highly automated systems require skilled technicians, dependable spare parts, software support, and regular preventive maintenance. Unexpected equipment failures can disrupt entire production lines and create costly downtime. Manufacturers must therefore evaluate total lifecycle costs rather than focusing exclusively on equipment purchase prices.
Fluctuating raw material and energy costs can also influence capital investment decisions. Food manufacturers facing margin pressure may postpone equipment upgrades despite potential long-term productivity benefits.
Market Opportunities
Smart manufacturing presents significant opportunities for companies operating in the food processing machinery market. Connected equipment equipped with sensors and monitoring technologies can generate valuable information regarding temperature, vibration, production speed, equipment condition, and energy consumption. Manufacturers can use these insights to improve preventive maintenance and production planning.
Demand for flexible processing lines also provides growth opportunities. Consumers increasingly seek convenience foods, healthier formulations, plant-based alternatives, premium products, and personalized food choices. Manufacturers therefore require equipment capable of accommodating multiple recipes, ingredients, product sizes, and production volumes without lengthy changeovers.
Sustainability represents another important opportunity. Energy-efficient motors, water-saving cleaning systems, heat recovery solutions, waste-reduction technologies, and equipment designed to minimize product losses can help food manufacturers reduce resource consumption. Equipment suppliers that combine productivity with measurable operational efficiency can strengthen their market position.
Company Insights
Competition within the food processing and handling equipment industry is influenced by equipment performance, automation capabilities, hygiene, customization, energy efficiency, service availability, and aftermarket support. Prominent companies associated with the global food processing equipment landscape include:
Recent Developments
A significant industry development is the growing integration of digital monitoring and automation technologies into food processing lines. Equipment manufacturers are strengthening intelligent control capabilities that allow processors to monitor machine performance, identify potential operating issues, improve production consistency, and reduce unplanned downtime. Greater connectivity between processing, handling, and packaging systems is supporting the transition toward integrated smart factories.
Another major development is the increasing focus on energy-efficient and hygienically designed equipment. Food processors are placing greater emphasis on machinery that reduces water, energy, cleaning time, and product waste while maintaining stringent sanitation standards. Equipment suppliers are consequently refining machine architecture, cleaning systems, automation functions, and production controls to address sustainability and food safety requirements simultaneously.
Conclusion
The food processing and handling equipment market is positioned for sustained expansion as food manufacturers respond to increasing consumption, automation requirements, food safety expectations, and changing consumer preferences. With the market anticipated to increase from US$ 132.7 Bn in 2026 to US$ 200.9 Bn by 2033 at a CAGR of 6.1%, manufacturers have strong incentives to invest in productive, hygienic, flexible, and digitally connected equipment. Automation, smart manufacturing, energy efficiency, sustainable processing, and integrated production lines are likely to remain central themes shaping the industry’s development. Equipment suppliers capable of combining reliable machinery with digital capabilities, lifecycle services, efficient resource utilization, and adaptable production technologies will be well positioned to address evolving requirements across the global food manufacturing sector.