Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Market Overview
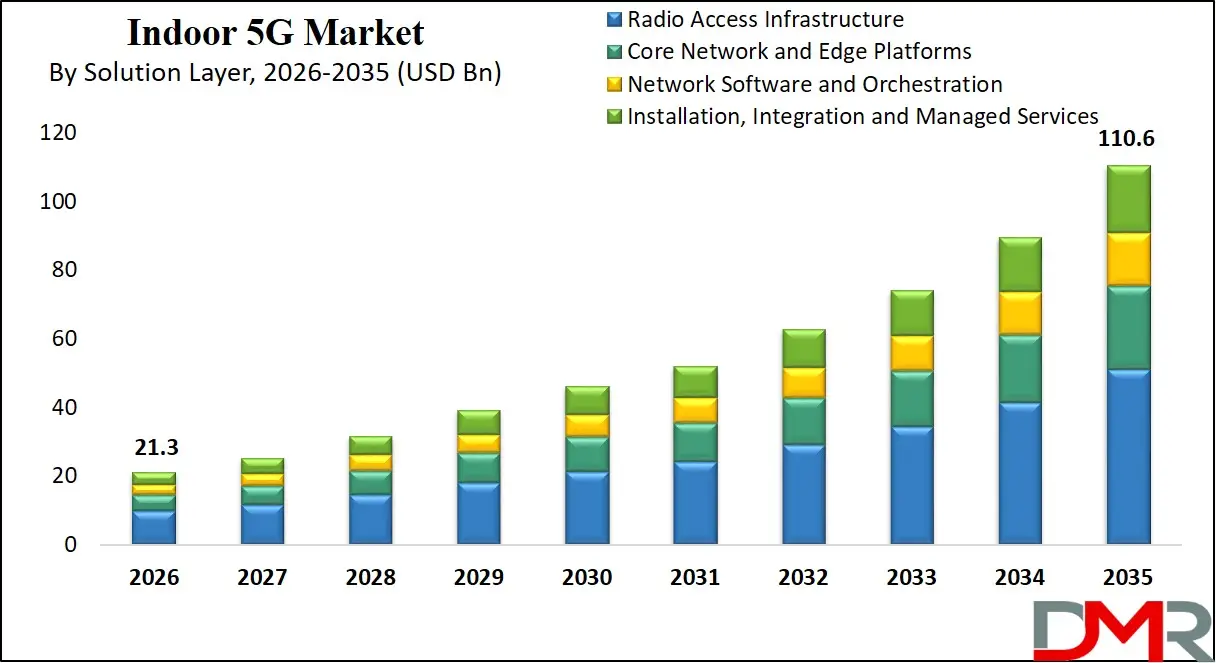
According to Dimension Market Research, the global Indoor 5G Market is expected to reach USD 21.3 billion in 2026 and expand at a CAGR of 20.1% through 2035, reaching USD 110.6 billion, driven by rising enterprise connectivity demand, private 5G networks, smart buildings, indoor wireless broadband, and high capacity in-building mobile network infrastructure.
Indoor 5G refers to the deployment of fifth-generation mobile network technology inside buildings and enclosed environments to deliver ultra-fast data speeds, low latency, high device density, and reliable wireless coverage where outdoor macro networks struggle to penetrate. It uses purpose-built indoor radio systems such as small cells and distributed antenna networks combined with local core and edge computing to support demanding digital workloads including real-time collaboration, immersive media, automation, connected machines, and secure enterprise communications across offices, hospitals, factories, campuses, and public venues.
The global Indoor 5G market represents the worldwide ecosystem of technologies, solutions, and services that enable high-performance wireless connectivity inside commercial, industrial, and institutional buildings. It includes radio access infrastructure, spectrum-optimized indoor networks, software platforms, edge computing, and professional services that together allow enterprises and property owners to deploy private and managed 5G environments.
From a market perspective, global indoor 5G adoption is expanding as enterprises seek greater control over network security, quality of service, and data localization while reducing dependence on traditional public cellular coverage. Industries such as manufacturing, healthcare, logistics, retail, and education are increasingly investing in indoor wireless broadband to enable automation, real-time analytics, connected equipment, digital twins, and immersive experiences.
Definition and Market Significance
Indoor 5G refers to the deployment of fifth-generation mobile network technology inside buildings and enclosed environments to deliver ultra-fast data speeds, low latency, high device density, and reliable wireless coverage where outdoor macro networks struggle to penetrate. It uses purpose-built indoor radio systems such as small cells and distributed antenna networks combined with local core and edge computing.
The importance of indoor 5G lies in its ability to provide high-performance wireless connectivity for demanding enterprise applications, including real-time collaboration, immersive media, industrial automation, connected machines, and secure communications. It enables organizations to support thousands of connected devices simultaneously while maintaining consistent performance and security.
Indoor 5G also supports broader digital transformation objectives by enabling smart buildings, industrial IoT, edge computing, and advanced enterprise applications that drive productivity, operational efficiency, and innovation across industries.
Looking for Something Specific? Get Free Sample:
https://dimensionmarketresearch.com/request-sample/indoor-5g-market/
Market Drivers
A major factor driving the Indoor 5G Market is enterprise digital transformation and private connectivity demand. Rapid digital transformation initiatives across industries are driving adoption of indoor 5G networks to support high-throughput connectivity, secure enterprise communication, and real-time data processing. Organizations increasingly favor private 5G solutions over traditional Wi-Fi to enable seamless cloud application access, edge computing integration, and high device density coverage in offices, campuses, and factories.
The growth of industrial IoT and automation is another key driver supporting market expansion. The proliferation of industrial IoT devices, robotics, and automated systems in manufacturing and logistics is accelerating demand for reliable in-building wireless networks. Indoor 5G’s ultra-low latency and robust wireless performance make it ideal for mission-critical applications such as predictive maintenance, autonomous guided vehicles, and connected sensors, enhancing operational efficiency and reducing downtime.
The increasing demand for secure enterprise networks, smart building technologies, and connected devices that require consistent high bandwidth is also contributing to market growth, along with regulatory support for shared spectrum and rising investments by telecom operators and neutral host providers.
Market Trends
The integration with edge computing and AI-driven networks is emerging as an important trend in the market. Indoor 5G networks are increasingly integrated with multi-access edge computing (MEC) and artificial intelligence for real-time network optimization, enhanced security, and localized data processing. This trend enhances performance for latency-sensitive applications, supports distributed analytics, and enables adaptive resource allocation based on traffic patterns.
Another significant trend is the adoption of neutral host and shared infrastructure models. Neutral host models, where multiple operators and enterprises share indoor 5G infrastructure, are gaining traction in high-density venues such as airports, stadiums, and convention centers. Shared wireless infrastructure lowers deployment costs, improves spectrum utilization, and ensures consistent high-capacity coverage for multiple stakeholders.
The growing deployment of private 5G networks and the integration of AI-driven orchestration and automation are also transforming the market, enabling enterprises to scale operations, improve cybersecurity, and deliver reliable high-performance indoor connectivity.
Market Restraints
Despite its strong growth potential, the Indoor 5G Market faces certain limitations. High deployment and infrastructure cost poses significant challenges. The initial investment required for indoor 5G infrastructure, including small cells, distributed antenna systems, and core network integration, remains a major restraint for many enterprises. The complexity of indoor wireless coverage planning, spectrum licensing fees, and professional services increases total cost of ownership, slowing adoption in cost-sensitive segments.
Technical challenges with network integration is another significant restraint. Integrating indoor 5G with existing IT networks and legacy systems poses technical challenges related to interoperability, spectrum management, and security. Ensuring seamless handover between outdoor and indoor networks while maintaining quality of service requires advanced network planning and expertise, limiting rapid deployment for some organizations.
In addition, the need for skilled personnel to manage and optimize complex indoor 5G environments can slow adoption, particularly among smaller enterprises with limited technical resources.
Market Opportunities
Private 5G as a service and managed connectivity solutions presents significant growth opportunities. Offering private 5G networks through managed services presents a significant market opportunity for service providers and system integrators. Enterprises looking to outsource deployment, maintenance, and optimization can leverage managed indoor 5G solutions to reduce operational burden, accelerate time to value, and scale wireless capacity based on evolving business needs.
Expansion into emerging vertical use cases is another promising opportunity. New applications in smart healthcare, AR/VR collaboration, immersive media, and real-time analytics open opportunities for indoor 5G adoption beyond traditional commercial and industrial sectors. Hospitals, educational campuses, and smart retail environments are increasingly deploying indoor wireless broadband to support advanced digital services and improve user experience.
Furthermore, the growth of neutral host models and the expansion of indoor 5G in public infrastructure such as airports, metro stations, and stadiums are expected to open new opportunities for market participants.
Segmentation
The Indoor 5G Market is categorized based on network architecture, spectrum band, network ownership model, deployment environment, solution layer, and application type.
By network architecture, small cell networks are expected to dominate with a 56.0% share in 2026 because they offer a highly flexible and cost-effective way to deliver high-capacity indoor 5G coverage. Distributed antenna systems also play a vital role, particularly in large venues and multi-tenant buildings where uniform coverage and multi-operator support are required.
By spectrum band, sub-6 GHz spectrum is anticipated to dominate with a 74.0% share in 2026 because it provides the best balance between coverage, penetration, and capacity for indoor environments. Millimeter wave spectrum, while holding a smaller share, plays a critical role in delivering extremely high data speeds and ultra-low latency for bandwidth-intensive indoor applications.
By network ownership model, private enterprise networks are expected to dominate with a 52.0% share in 2026 because organizations increasingly want full control over their indoor 5G environments to meet specific performance, security, and data governance requirements. Operator-managed indoor networks remain an important part of the market.
By deployment environment, commercial real estate is expected to dominate with a 36.0% share in 2026 as offices, business parks, shopping malls, hotels, and mixed-use developments increasingly rely on high-performance indoor wireless connectivity. Industrial buildings also represent a significant and fast-growing deployment environment.
By solution layer, radio access infrastructure is expected to dominate with a 46.0% share in 2026 because it forms the physical foundation of every indoor 5G network. Core network and edge platforms play a crucial supporting role by enabling intelligent traffic management, security, and real-time data processing.
By application type, high-density connectivity is expected to dominate with a 29.0% share in 2026 as indoor environments increasingly need to support large numbers of simultaneous users and connected devices. Industrial automation and robotics represent a critical application area for indoor 5G.
Regional Analysis
Asia Pacific is expected to lead the global Indoor 5G market with a 38.0% revenue share in 2026, driven by rapid digitalization, large-scale 5G infrastructure investments, and strong demand from manufacturing, smart buildings, and enterprise connectivity across countries such as China, Japan, South Korea, and India. The region has a high concentration of technology-intensive industries, dense urban development, and growing adoption of private 5G networks in factories, logistics centers, and commercial complexes. Japan’s market is expected to reach USD 2.0 billion in 2026 at a CAGR of 20.0%.
North America is emerging as a region with significant growth in the global Indoor 5G market, supported by strong enterprise adoption, widespread deployment of private 5G networks, and advanced cloud and edge computing infrastructure. Large investments by telecom operators, neutral host providers, and technology companies are accelerating indoor wireless upgrades across offices, healthcare facilities, industrial plants, and public venues. The US market is expected to reach USD 6.3 billion in 2026, reaching USD 29.7 billion in 2035 at a CAGR of 18.8%.
Europe holds a substantial share of the indoor 5G market, expected to reach USD 5.9 billion in 2026 at a CAGR of 15.0%. Demand is rising across commercial offices, retail complexes, healthcare facilities, and public venues where reliable mobile broadband and low-latency networks are essential for digital operations. The adoption of private 5G networks and managed indoor solutions is helping organizations improve productivity, support cloud applications, and deliver better user experiences.
Latin America and the Middle East & Africa are gradually adopting indoor 5G solutions as digital infrastructure improves and awareness of private wireless benefits grows, with Brazil, Mexico, the UAE, and Saudi Arabia emerging as key markets.
Competitive Landscape
The competitive landscape of the global Indoor 5G market is characterized by intense innovation, strategic partnerships, and a strong focus on integrated network solutions that combine radio infrastructure, software platforms, and managed services. Market participants compete on the basis of network performance, deployment flexibility, spectrum efficiency, and the ability to support private and hybrid 5G environments for enterprises.
Prominent players include Ericsson, Huawei Technologies, Nokia, Samsung Electronics, ZTE Corporation, CommScope, Corning Incorporated, Comba Telecom, AT&T, Airspan Networks, SOLiD, Dali Wireless, Nextivity, JMA Wireless, Liteon Technology, ALCAN, Extenet Systems, Mavenir, Boingo Wireless, and Cisco Systems. Recent developments include Inseego’s launch of an advanced indoor 5G fixed wireless access router (December 2025), Ericsson’s introduction of a new compact indoor 5G radio and baseband solution (October 2025), Airspan Networks’ acquisition of Corning’s Wireless business (April 2025), and Airspan Networks’ agreement to acquire Corning’s in-building wireless business (February 2025).
Technological Advancements
Rapid advancements in AI-driven network management, edge computing, and network virtualization are transforming the Indoor 5G market. AI-driven network management platforms analyze real-time traffic, user behavior, and radio conditions to automatically optimize spectrum allocation, power levels, and handovers between small cells and antennas. This improves coverage quality, reduces interference, and ensures consistent performance in complex indoor environments.
AI also enables predictive maintenance of indoor 5G infrastructure by detecting anomalies in radio equipment, edge servers, and network performance before failures occur, minimizing downtime and operational costs. In smart factories, AI-powered analytics running on edge computing platforms connected to indoor 5G networks support quality inspection, robotics control, and production optimization with ultra-low latency.
Consumer Adoption Patterns
Enterprises across manufacturing, healthcare, logistics, retail, education, and commercial real estate are increasingly adopting indoor 5G networks to support digital transformation, industrial automation, smart building systems, and high-density connectivity. The growing availability of private 5G and managed indoor network solutions is making these technologies more accessible across enterprise segments.
Regulatory Environment
Regulatory frameworks across different regions, including spectrum allocation policies, licensing requirements, and data protection regulations, significantly influence the Indoor 5G market. Supportive spectrum policies, including shared spectrum access and private network licensing, are enabling enterprise adoption and shaping market development.
Market Challenges
The Indoor 5G market faces challenges related to high deployment and infrastructure costs, technical complexity in network integration, skilled workforce shortages, and the need for continuous investment in technology and network optimization. Additionally, ensuring seamless handover between outdoor and indoor networks and maintaining security across private 5G environments remain ongoing challenges.
Future Outlook
The future of the Indoor 5G Market remains exceptionally promising as enterprises continue to prioritize digital transformation and private wireless connectivity. Increasing adoption of private 5G networks, growth of edge computing and AI-driven network management, expansion into emerging vertical use cases, and the rising deployment of neutral host models are expected to drive strong market growth during the forecast period, with the market projected to reach USD 110.6 billion by 2035 at a CAGR of 20.1%.
FAQs
What is the expected size of the Indoor 5G Market in 2026?
The market is expected to reach USD 21.3 billion in 2026.
What is the projected market value by 2035?
The market is forecast to reach USD 110.6 billion by 2035.
What is the CAGR of the Indoor 5G Market?
The market is expected to grow at a CAGR of 20.1% during 2026–2035.
Which network architecture segment dominates the market?
Small cell networks are expected to dominate with a 56.0% share in 2026.
Which region leads the global Indoor 5G market?
Asia Pacific is expected to lead with a 38.0% revenue share in 2026.
Summary of Key Insights
The global Indoor 5G Market is expected to grow from USD 21.3 billion in 2026 to USD 110.6 billion by 2035, recording a CAGR of 20.1% during the forecast period. Small cell networks lead the network architecture segment with 56.0% share, while sub-6 GHz spectrum dominates with 74.0% share. Private enterprise networks lead the ownership model with 52.0% share, commercial real estate leads deployment environments with 36.0% share, and high-density connectivity leads applications with 29.0% share. Asia Pacific holds the largest regional share with 38.0% of global revenue in 2026, while North America is projected as a significant growth region. The US market is projected to reach USD 29.7 billion by 2035 at a CAGR of 18.8%.
Purchase the Full Report
https://dimensionmarketresearch.com/checkout/indoor-5g-market/