Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
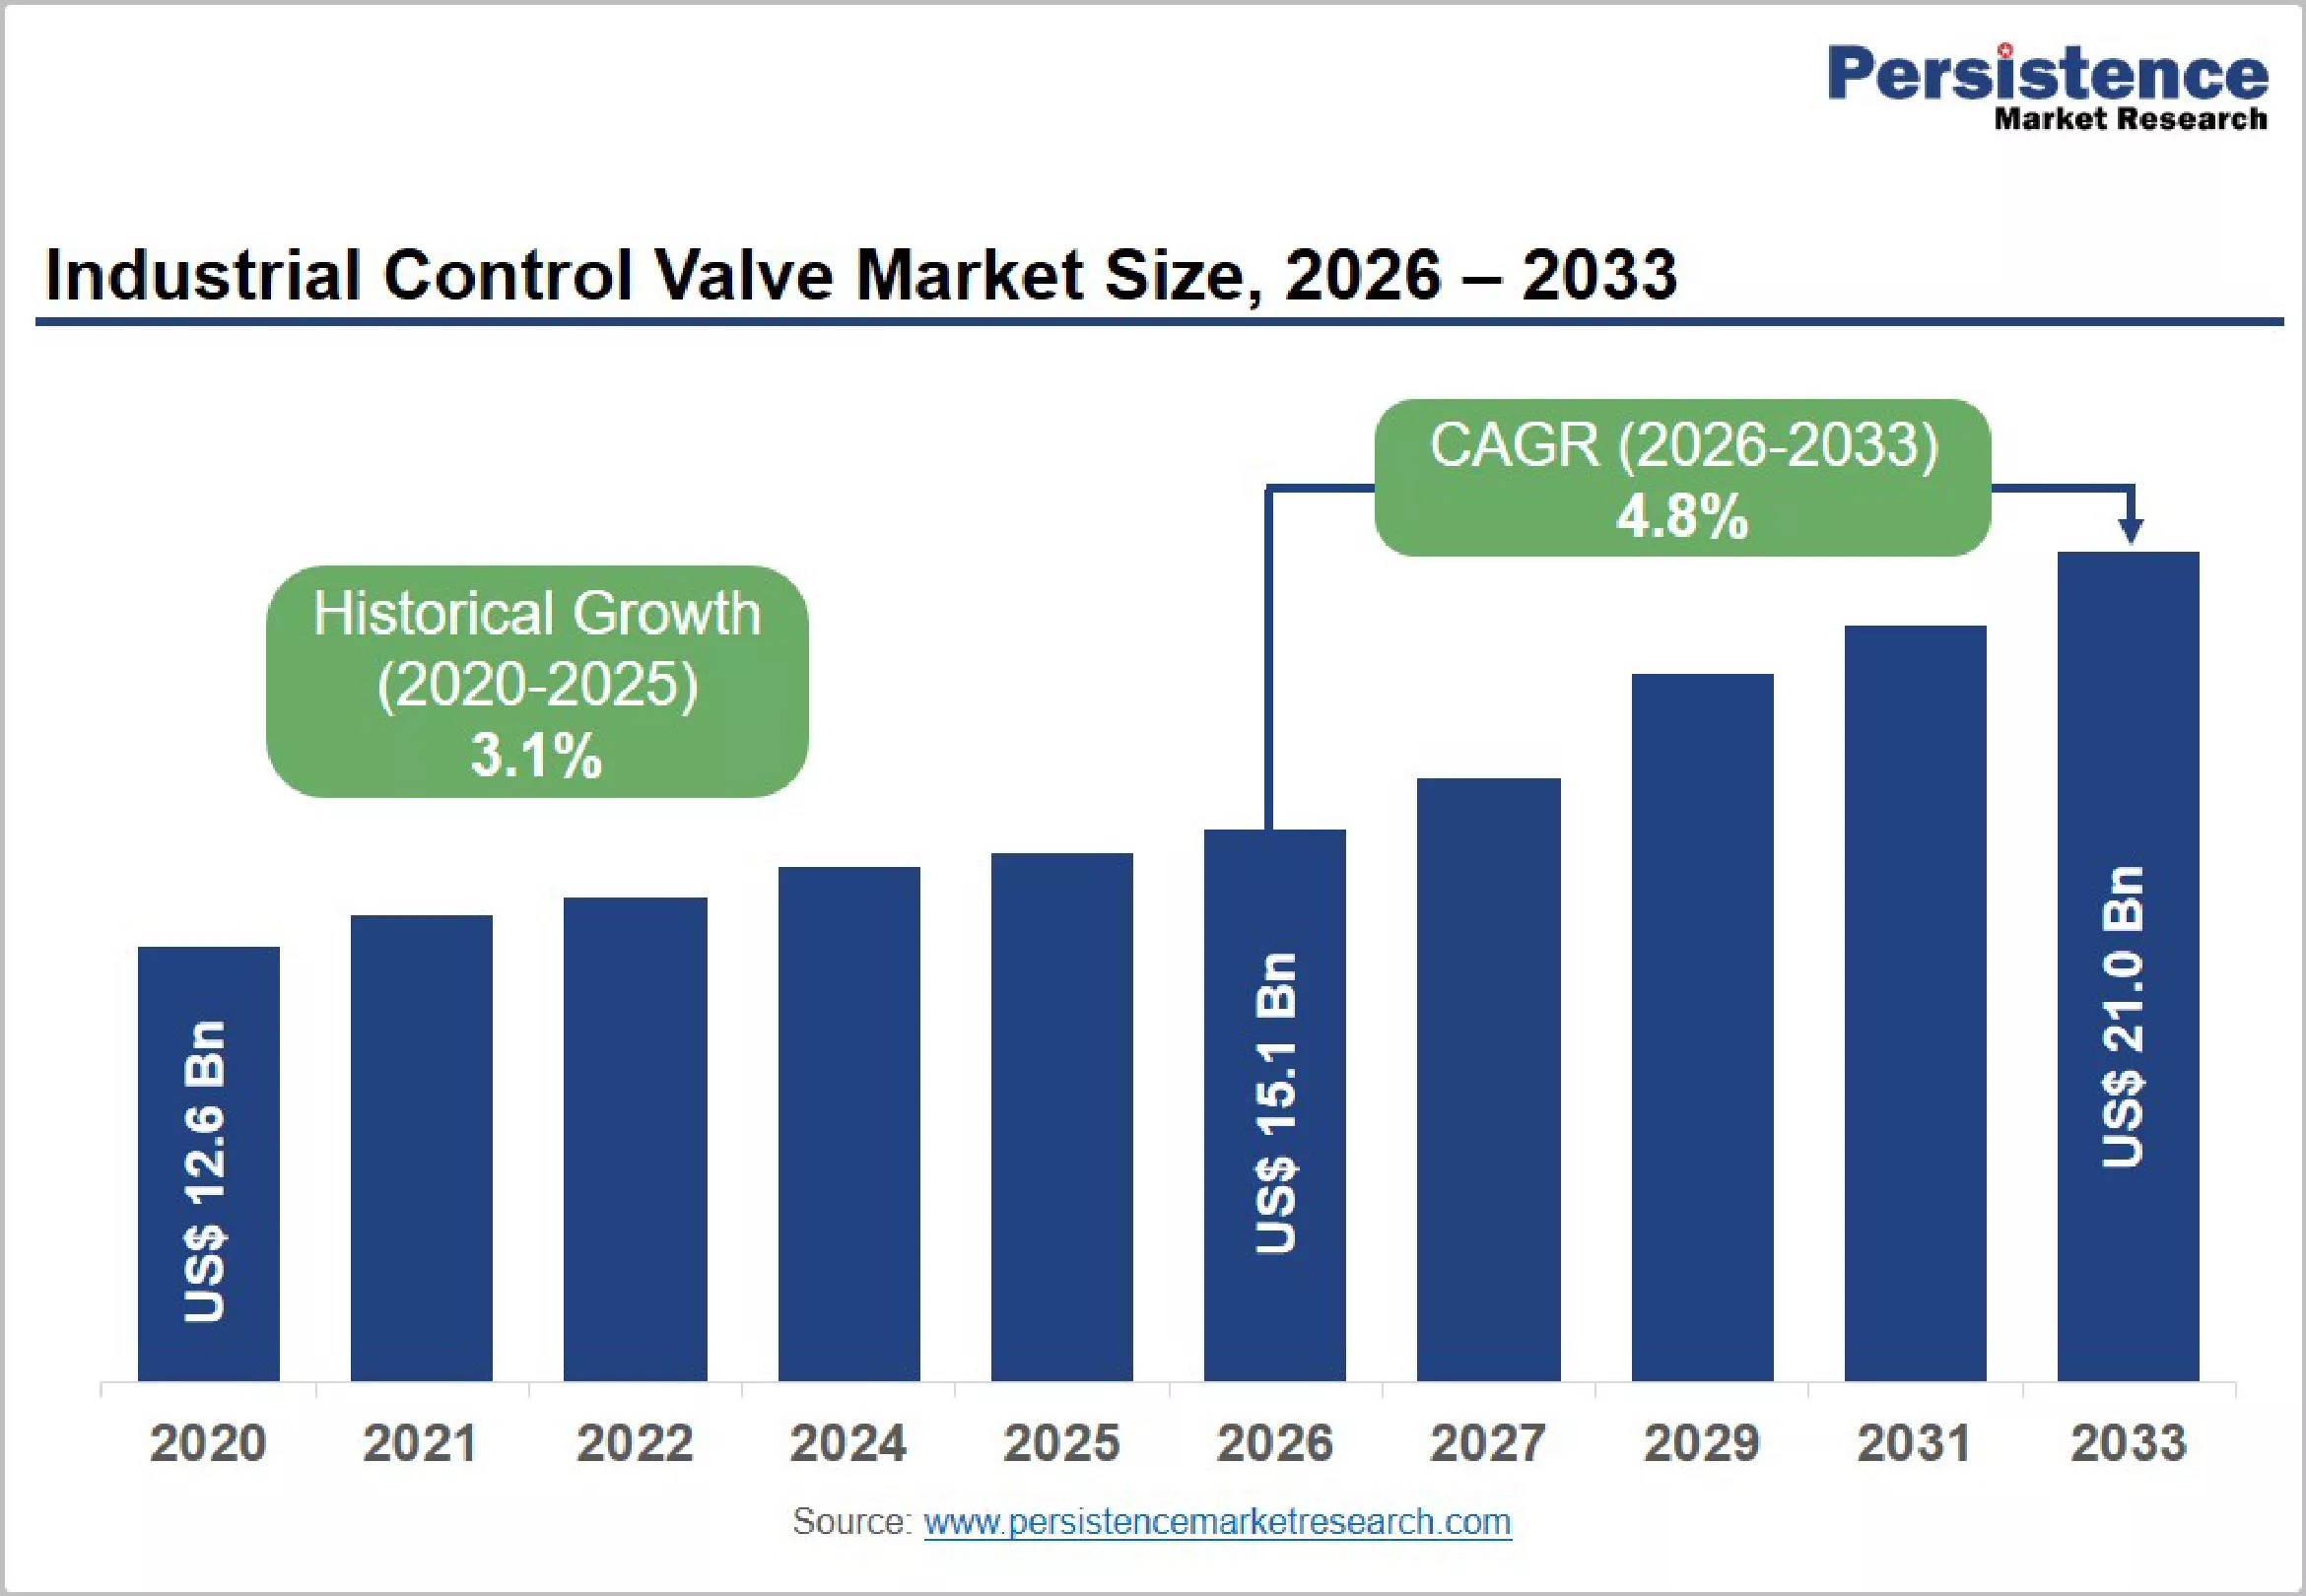
The global industrial control valve market size is expected to be valued at US$15.1 billion in 2026 and is projected to reach US$21 billion by 2033, expanding at a CAGR of 4.8% between 2026 and 2033. Industrial control valves are essential components of modern process systems, regulating the flow, pressure, temperature, and level of liquids, gases, and steam. Their importance extends across oil and gas, chemicals, power generation, water and wastewater treatment, pharmaceuticals, food processing, and other process industries. Increasing investment in industrial automation, oil and gas infrastructure, energy transition projects, and water management modernization is supporting sustained demand for reliable control valve technologies.
Oil and gas remains a major application area because valves are required throughout upstream, midstream, and downstream operations for reliable process control and safety. Increasing modernization of refineries, pipelines, processing facilities, and energy infrastructure is strengthening replacement and new-installation demand. Asia Pacific represents a significant growth region, supported by industrialization, manufacturing expansion, energy infrastructure investment, and large-scale water management projects. At the same time, North America and Europe continue to generate substantial demand through automation upgrades, aging infrastructure replacement, digitalization, and investments aimed at improving energy and operational efficiency.
𝐅𝐑𝐄𝐄 𝐒𝐚𝐦𝐩𝐥𝐞 & 𝐄𝐱𝐩𝐥𝐨𝐫𝐞 𝐭𝐡𝐞 𝐋𝐚𝐭𝐞𝐬𝐭 𝐌𝐚𝐫𝐤𝐞𝐭 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬:https://www.persistencemarketresearch.com/samples/37218
Key Highlights from the Report
Industrial Control Valve Market Segmentation
The industrial control valve market can be segmented by valve type into globe valves, ball valves, butterfly valves, gate valves, diaphragm valves, and other specialized control valves. Globe valves are widely deployed where accurate throttling and flow regulation are required, while ball valves provide strong shutoff capabilities and are suitable for numerous industrial processes. Butterfly valves are attractive for large-diameter applications due to their compact design and relatively low weight. Selection ultimately depends on pressure, temperature, flow characteristics, fluid composition, maintenance requirements, and the operating environment.
Based on actuation, the market includes pneumatic, electric, hydraulic, and manual valve systems. Pneumatic actuators remain widely used in process industries because of their rapid response and suitability for demanding industrial environments. Electric actuators are gaining attention alongside plant electrification and automation because they can provide accurate positioning and support integration with digital control platforms. Hydraulic systems remain important in applications demanding high actuation force and reliable operation under challenging conditions.
By end-use industry, demand is distributed across oil and gas, chemicals and petrochemicals, power generation, water and wastewater treatment, pharmaceuticals, food and beverages, metals and mining, and other manufacturing industries. Oil and gas represents a particularly important application because precise fluid control is essential throughout production, transportation, processing, and refining. Water and wastewater treatment is another increasingly important segment as governments and utilities modernize aging networks and expand treatment infrastructure.
Regional Insights
Asia Pacific is positioned as a major growth center for the industrial control valve industry, supported by rapid industrialization and investments in manufacturing, energy, chemicals, water infrastructure, and urban utilities. China and India represent important demand centers as infrastructure development and industrial capacity expansion increase the need for advanced flow control solutions. Growing adoption of automated manufacturing technologies is also creating opportunities for smart valve systems capable of delivering more accurate and efficient process control.
North America represents an established industrial control valve market with substantial demand from oil and gas, chemicals, power generation, water treatment, and advanced manufacturing. Modernization of aging infrastructure, expansion of automation, and investment in energy projects support replacement and upgrade opportunities. Digital transformation across process facilities is also encouraging adoption of valves equipped with sensors, positioners, diagnostics, and remote monitoring functionality.
Europe is characterized by strong emphasis on energy efficiency, industrial modernization, environmental performance, and process optimization. Investments in renewable energy, hydrogen infrastructure, chemicals, pharmaceuticals, and water management are generating specialized valve requirements. Latin America and the Middle East & Africa also provide opportunities, particularly through oil and gas development, mining, water infrastructure, petrochemical investment, and broader industrial expansion.
Industrial Control Valve Market Drivers
One of the strongest drivers for the industrial control valve market is increasing capital investment in oil and gas infrastructure. Exploration, production, pipelines, LNG infrastructure, processing plants, refineries, and petrochemical complexes require dependable valve systems capable of controlling fluids under demanding pressure and temperature conditions. Expansion and modernization of these assets therefore creates sustained requirements for control valves and related automation equipment.
Industrial automation represents another major growth driver. Manufacturers increasingly seek real-time process visibility, consistent production quality, lower downtime, and improved operational efficiency. Automated valves integrated with industrial control systems allow operators to adjust process conditions more accurately while reducing manual intervention. The transition toward smart factories and digitally connected industrial facilities is consequently increasing demand for intelligent valve technologies.
Water management modernization is also supporting market expansion. Aging municipal water networks, wastewater treatment requirements, industrial water reuse, desalination, and increasing pressure to manage water efficiently require reliable flow-control equipment. Control valves help regulate pressure and flow throughout water distribution and treatment infrastructure, making them critical components of modernization programs.
Industrial Control Valve Market Restraints
High initial investment and maintenance requirements can restrain adoption of advanced industrial control valves, particularly among smaller operators. Sophisticated valves incorporating actuators, sensors, digital positioners, and diagnostic systems may involve considerable procurement and integration costs. Industries operating older facilities can also face compatibility challenges when integrating intelligent valves with legacy process-control infrastructure.
Harsh operating environments present another challenge. Industrial valves may encounter corrosive chemicals, abrasive materials, high temperatures, extreme pressures, and continuous operating cycles. These conditions can cause erosion, leakage, corrosion, and component degradation if products are improperly selected or maintained. Manufacturers must therefore balance durability, accuracy, material performance, maintenance requirements, and lifecycle costs.
Industrial Control Valve Market Opportunities
The rise of smart control valves and Industrial Internet of Things technologies is creating significant opportunities. Sensors, digital positioners, and connected monitoring systems can provide continuous information about valve condition and operating performance. This data can support predictive maintenance strategies, helping industrial operators identify potential failures before they result in unplanned production interruptions.
Energy transition projects represent another important opportunity. Investments in hydrogen, carbon management, renewable fuels, alternative energy infrastructure, and lower-emission industrial processes are creating new flow-control requirements. Manufacturers capable of developing valves suited to challenging gases, pressures, temperatures, and process conditions can benefit from the evolving energy landscape.
Water and wastewater modernization offers additional long-term opportunities. Population growth, urbanization, water scarcity, industrial water recycling, and aging utility networks are encouraging investment in water infrastructure. Advanced control valves can support accurate flow management, leakage reduction, pressure optimization, and automated treatment processes.
Company Insights
The industrial control valve market features global automation companies and specialized flow-control manufacturers competing through product performance, application expertise, digital capabilities, lifecycle services, and distribution networks. Key participants include:
Competition is increasingly influenced by smart valve capabilities, reliability, predictive diagnostics, energy efficiency, aftermarket services, and the ability to provide customized solutions for specific industrial processes.
Recent Developments in the Industrial Control Valve Market
One important development across the market is the growing integration of digital valve positioners, sensors, and predictive diagnostics into industrial flow-control systems. Manufacturers are increasingly developing intelligent valve solutions capable of providing real-time performance data, supporting condition monitoring, and helping plant operators optimize preventive and predictive maintenance programs.
Another notable development is increasing product development for energy-transition applications, including hydrogen and other emerging low-carbon industrial systems. These applications can introduce demanding operating requirements related to pressure, sealing, material compatibility, and leakage prevention. Valve manufacturers are therefore focusing on engineering solutions that can address evolving process conditions while maintaining safety and reliability.
Conclusion
The industrial control valve market is positioned for steady expansion as industrial automation, oil and gas infrastructure investment, energy transition initiatives, and water management modernization reshape process industries worldwide. With market size expected to rise from US$15.1 billion in 2026 to US$21 billion by 2033 at a CAGR of 4.8%, demand will increasingly favor reliable, efficient, and digitally enabled flow-control technologies. Oil and gas applications remain a major source of demand, while Asia Pacific provides significant expansion opportunities through industrialization and infrastructure investment. As manufacturers strengthen smart valve capabilities, predictive diagnostics, specialized materials, and energy-transition solutions, industrial control valves will remain critical components for improving process safety, operational reliability, resource efficiency, and industrial productivity.