Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
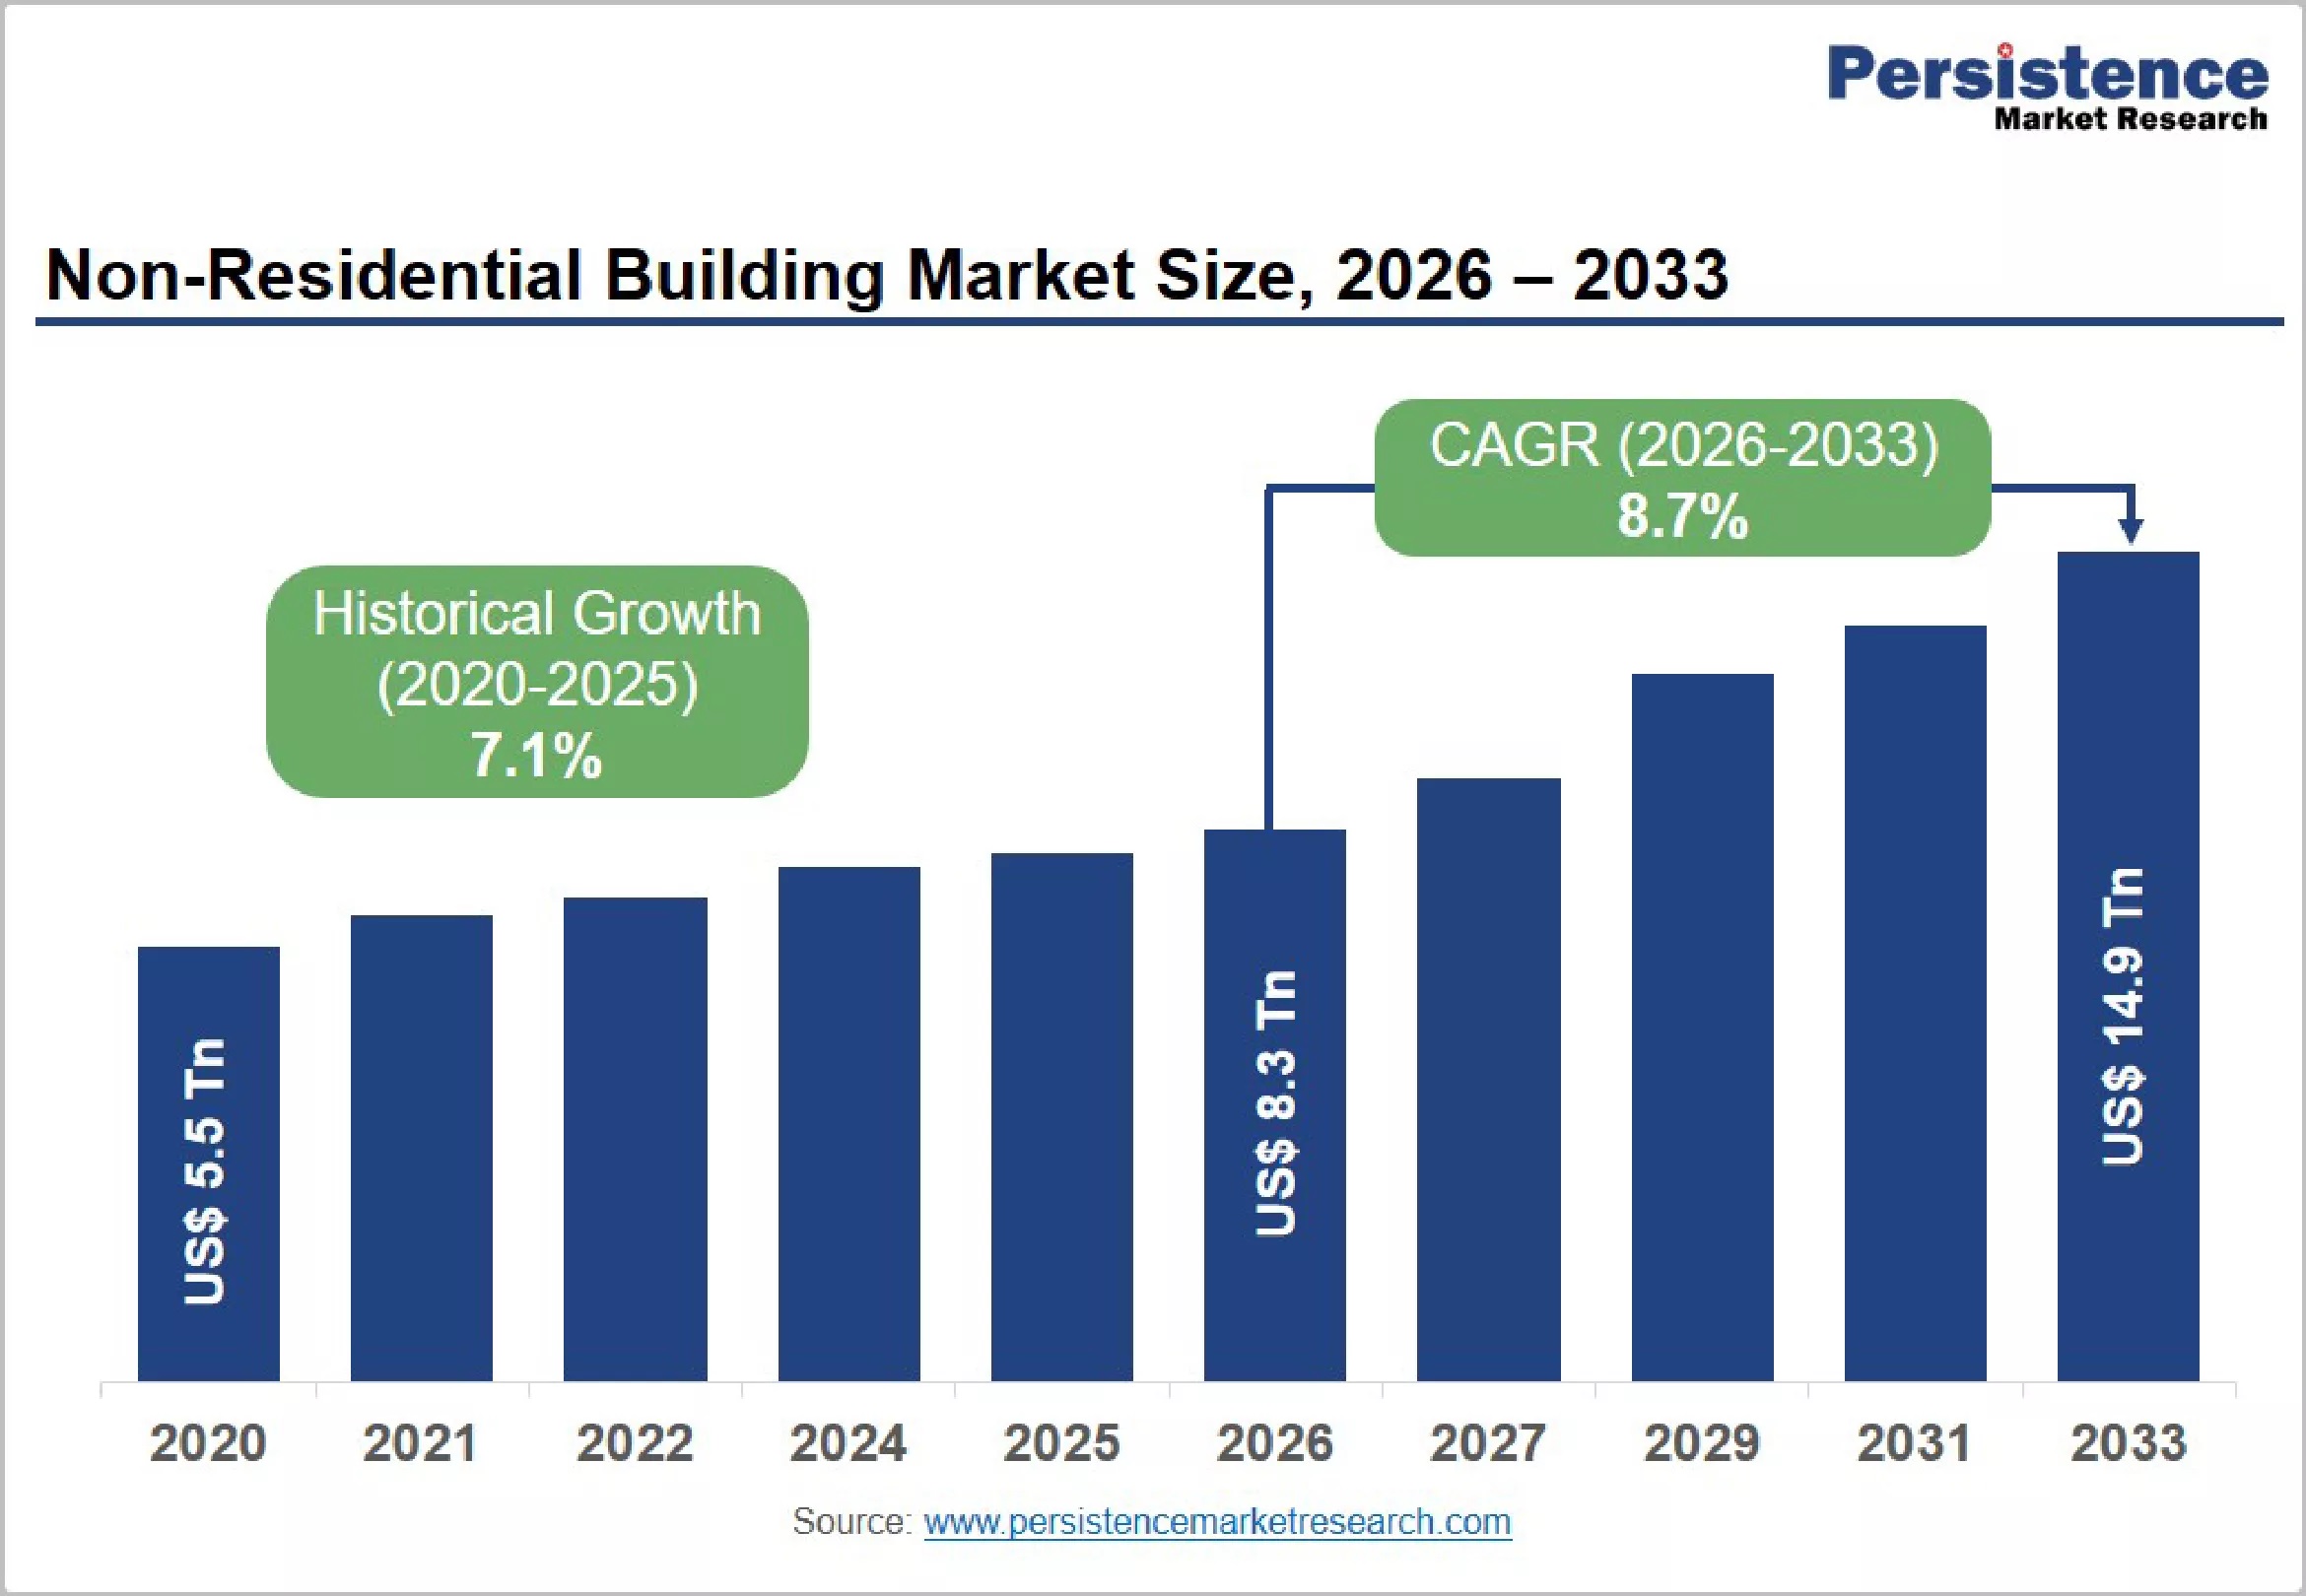
The global Non-Residential Building Market is valued at US$ 8.3 trillion in 2026 and is projected to reach US$ 14.9 trillion by 2033, expanding at a CAGR of 8.7% during the forecast period. The market encompasses construction and development of commercial, institutional, industrial, hospitality, healthcare, educational, retail, office, and other buildings intended primarily for business or public purposes. Accelerating urban infrastructure investment, supportive public spending, and a decisive transition toward energy-efficient assets are strengthening the market outlook. Growing urban populations are creating requirements for offices, hospitals, schools, warehouses, hotels, data-oriented facilities, and modern retail infrastructure, while developers increasingly emphasize sustainability, operational efficiency, and lifecycle performance.
Commercial construction represents a significant application area as urban business districts, offices, retail properties, hospitality facilities, and mixed-use developments expand. Institutional construction is also gaining importance as governments and private organizations invest in healthcare and education infrastructure. From a geographical perspective, Asia Pacific represents a major growth region due to rapid urbanization, expanding cities, industrial development, infrastructure investment, and continued demand for modern commercial and institutional buildings. At the same time, mature construction markets are being reshaped by renovation, energy-efficiency improvements, smart building technologies, and redevelopment of aging properties. These factors collectively create opportunities across new construction, modernization, and sustainable building projects.
𝐅𝐑𝐄𝐄 𝐒𝐚𝐦𝐩𝐥𝐞 & 𝐄𝐱𝐩𝐥𝐨𝐫𝐞 𝐭𝐡𝐞 𝐋𝐚𝐭𝐞𝐬𝐭 𝐌𝐚𝐫𝐤𝐞𝐭 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬:https://www.persistencemarketresearch.com/samples/37228
Key Highlights from the Report
Non-Residential Building Market Segmentation
The Non-Residential Building Market segmentation can be evaluated by building type, construction activity, ownership, and end-use application. By building type, the industry covers commercial buildings, institutional facilities, industrial structures, healthcare buildings, educational facilities, hospitality properties, retail spaces, offices, warehouses, and other specialized structures. Commercial buildings account for substantial construction activity because economic development and urban expansion generate continuous requirements for office spaces, retail centers, hotels, entertainment facilities, and mixed-use properties.
Institutional buildings form another important segment and include hospitals, educational institutions, government facilities, and other public-service properties. Population growth and expanding urban communities are increasing requirements for healthcare and education infrastructure. Governments are also allocating resources toward upgrading existing public assets, supporting both new construction and renovation opportunities within the non-residential construction industry.
Based on construction activity, the market can broadly be viewed through new construction and renovation or modernization projects. New construction is supported by expanding cities, new business districts, manufacturing development, and infrastructure programs. Renovation is becoming increasingly relevant in developed markets, where aging commercial and institutional buildings require energy-efficiency improvements, structural upgrades, digital building systems, and modernization.
Industrial and logistics buildings are also gaining strategic relevance as manufacturing, distribution, warehousing, and supply-chain networks evolve. Businesses increasingly require modern facilities capable of supporting automation, efficient material movement, digital operations, and flexible production requirements. This creates opportunities for contractors, engineering companies, building material providers, and technology suppliers serving the commercial construction ecosystem.
Regional Insights
Asia Pacific remains an important region for the Non-Residential Building Market, supported by rapid urban development, infrastructure expansion, industrialization, and growing demand for commercial and public facilities. Expansion of metropolitan areas creates requirements for office buildings, hospitals, educational facilities, hotels, retail properties, industrial buildings, and logistics infrastructure. Public infrastructure programs and private real estate investment further contribute to construction activity.
North America is characterized by demand for commercial property modernization, institutional infrastructure, industrial facilities, warehouses, healthcare buildings, and energy-efficient construction. Renovation and redevelopment represent important areas of activity as building owners seek to improve energy performance, integrate smart technologies, and enhance asset functionality. Continued investment in manufacturing and logistics facilities also supports the regional non-residential construction outlook.
Europe is increasingly influenced by sustainable construction and energy-efficiency requirements. Building owners and developers are focusing on improving the environmental performance of commercial and institutional properties through renovation, efficient building systems, modern insulation, and smarter energy management. These trends support demand for green building materials and advanced construction technologies.
Other developing regions provide long-term opportunities as urban populations expand and governments invest in transportation-linked infrastructure, healthcare, education, tourism, commercial development, and industrial capacity. Improving urban infrastructure can encourage additional private-sector construction investment and create broader demand across the building value chain.
Non-Residential Building Market Drivers
A primary driver of the market is accelerating urban infrastructure investment. Urban expansion creates demand for commercial offices, educational institutions, hospitals, hotels, retail properties, warehouses, manufacturing facilities, and government buildings. As cities grow, construction activity extends beyond basic infrastructure toward specialized facilities needed to support economic and social development. Supportive public spending further strengthens the market by financing institutional and infrastructure-related projects.
The shift toward energy-efficient buildings represents another significant growth driver. Developers and property owners increasingly evaluate buildings based on lifecycle operating costs, energy consumption, occupant comfort, sustainability, and long-term asset value. This transition is encouraging the adoption of efficient HVAC systems, improved insulation, smart building controls, efficient lighting, renewable-energy integration, and advanced construction materials.
Market Restraints
Despite favorable growth prospects, the Non-Residential Building Market faces challenges associated with construction costs, financing conditions, material availability, workforce constraints, and project complexity. Large commercial and institutional developments require substantial capital investment and extended development timelines. Higher financing costs or uncertain economic conditions can delay project approvals and influence private-sector construction decisions.
Volatility in building material prices and shortages of skilled construction professionals can also affect project schedules and profitability. Large projects require coordination among architects, engineers, contractors, technology providers, material suppliers, regulators, and property owners. Delays in permitting, procurement, design changes, or material delivery can increase overall construction costs and extend completion schedules.
Market Opportunities
The growing focus on green buildings and sustainable construction creates substantial opportunities across the market. Developers are increasingly interested in properties that reduce energy consumption while improving operational efficiency and environmental performance. This creates opportunities for providers of sustainable building materials, energy management technologies, smart HVAC systems, advanced insulation, building automation, and renewable-energy solutions.
Modernization of aging non-residential properties provides another important opportunity. Existing offices, hospitals, educational buildings, hotels, government facilities, and retail properties can be upgraded with smart technologies and energy-efficient systems rather than being completely replaced. Industrial and logistics expansion also creates opportunities for specialized construction companies capable of developing technologically advanced manufacturing and distribution facilities.
Company Insights
The competitive landscape includes global engineering, construction, infrastructure, and building development companies competing through project execution capabilities, technical expertise, geographical presence, sustainable construction practices, and experience with complex projects.
Recent Developments
A significant recent development across the non-residential construction industry is the growing integration of smart building technologies into new and renovated commercial properties. Building automation, intelligent energy management, connected HVAC systems, digital monitoring, and data-driven facility management are increasingly being incorporated to improve operational performance and reduce long-term energy consumption.
Another important development is the increasing emphasis on low-carbon and energy-efficient construction. Developers, contractors, governments, and building owners are placing greater attention on sustainable materials, building lifecycle performance, energy-efficient systems, and renovation of aging properties. This transition is influencing construction specifications and creating demand for innovative building technologies.
Conclusion
The global Non-Residential Building Market is positioned for strong expansion as urbanization, infrastructure investment, public spending, commercial development, and sustainability requirements reshape the construction landscape. With the market valued at US$ 8.3 trillion in 2026 and projected to reach US$ 14.9 trillion by 2033, expanding at a CAGR of 8.7%, demand is expected to remain supported by commercial, institutional, industrial, healthcare, education, and infrastructure-related construction. Energy-efficient assets, smart building technologies, sustainable materials, and modernization of existing properties are becoming increasingly important to market development. As cities expand and governments and businesses invest in modern facilities, the non-residential construction sector is expected to generate opportunities for contractors, developers, engineering companies, technology providers, and building material manufacturers throughout the forecast period.