Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
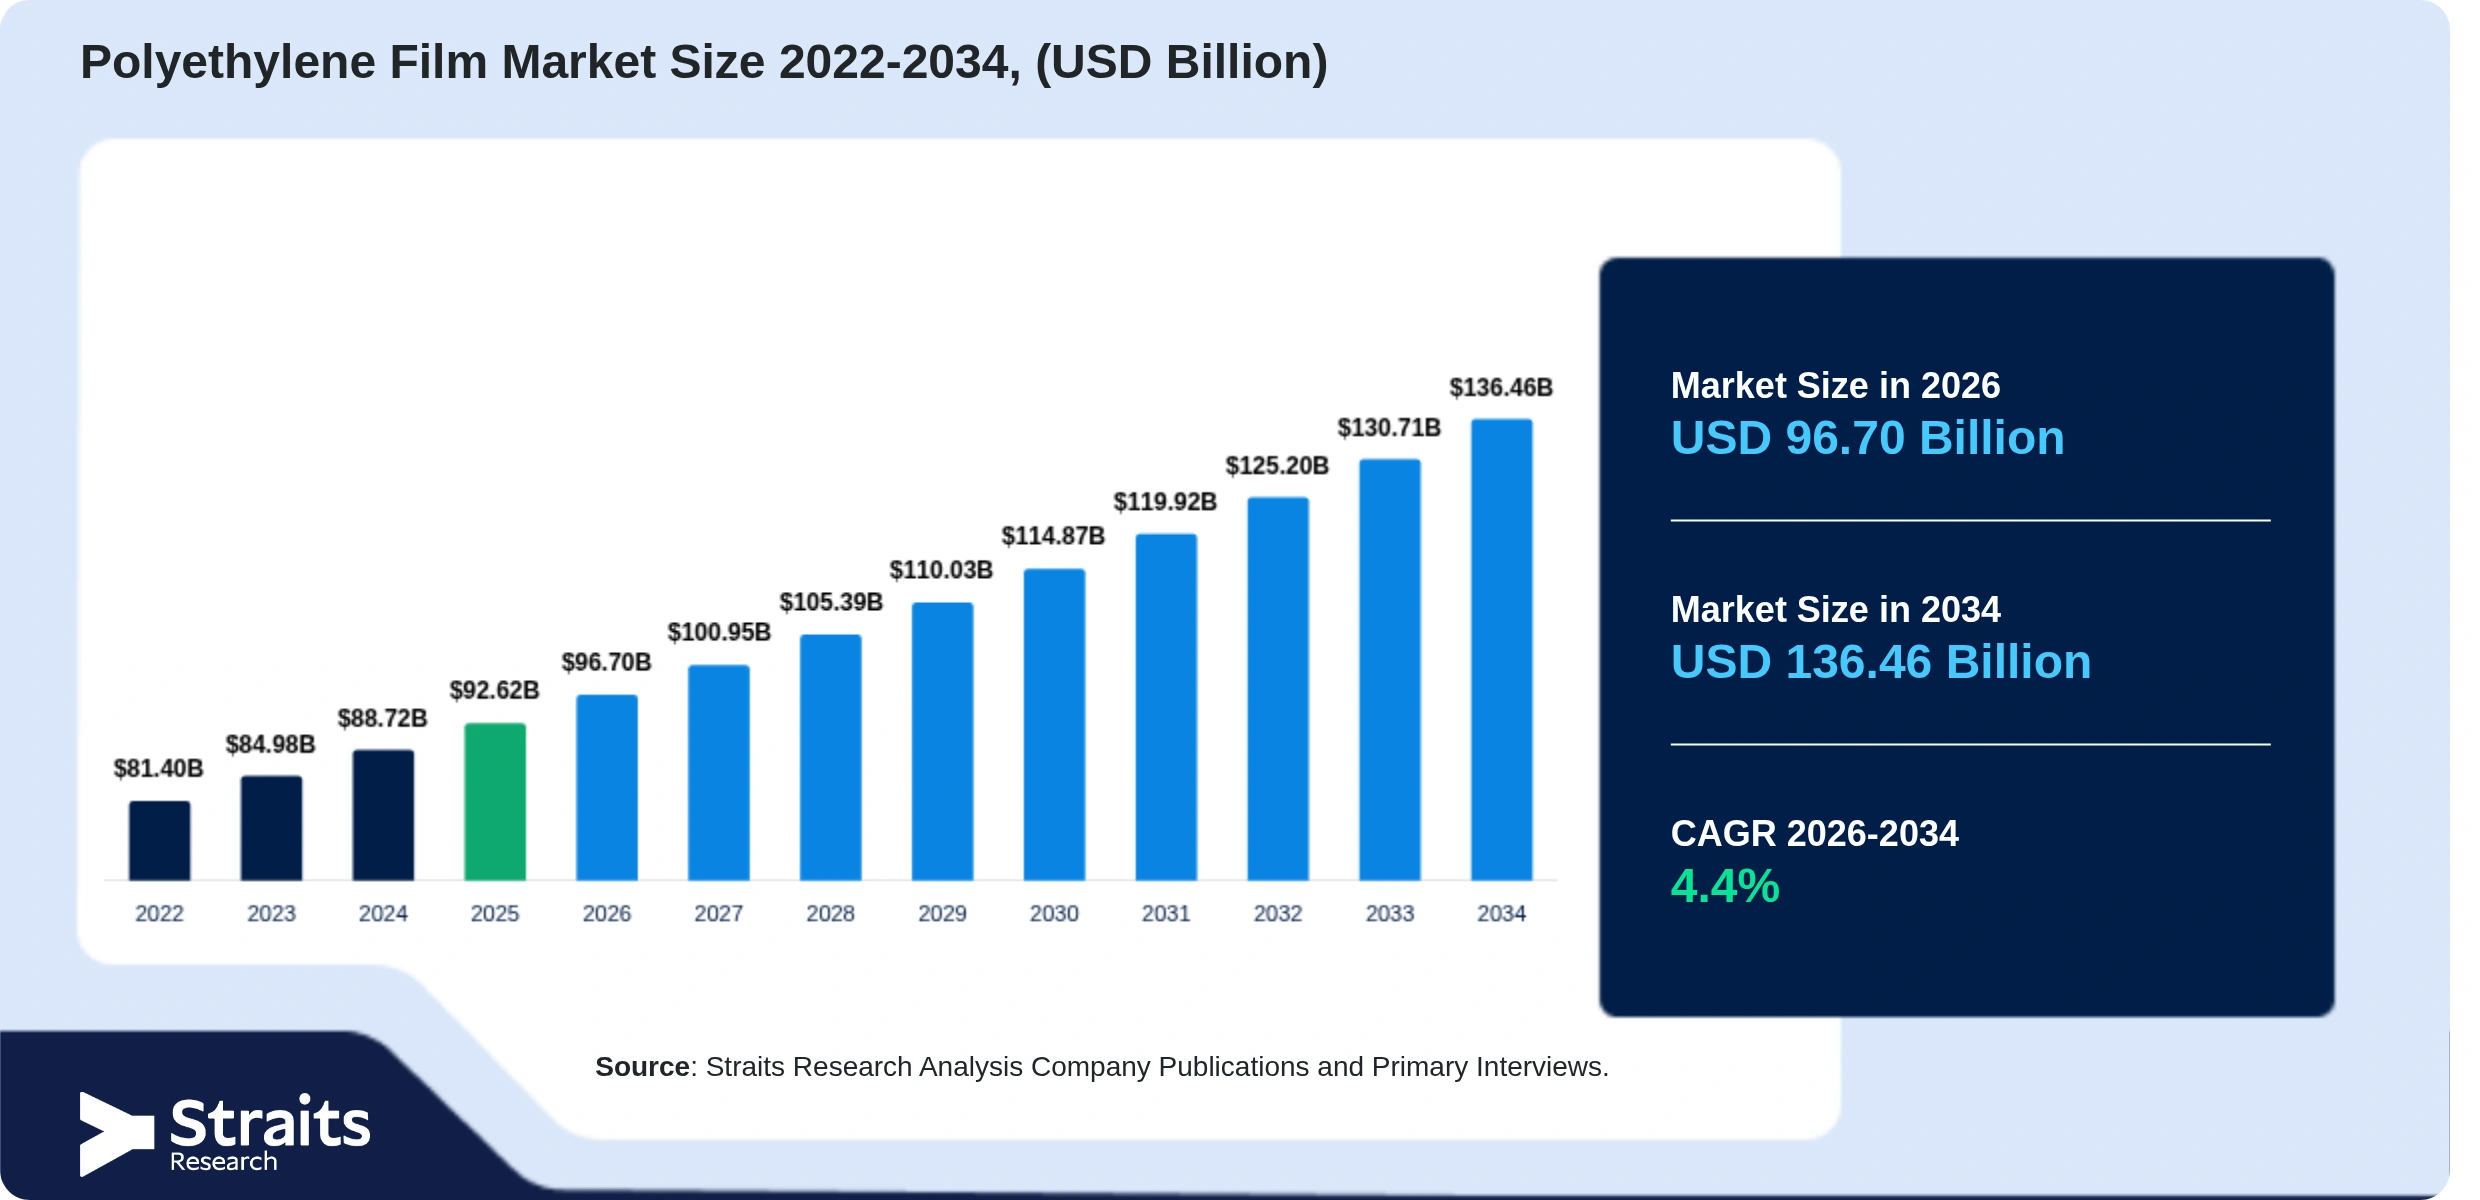
The global polyethylene film market is projected to reach USD 136.46 billion by 2034, growing at a 4.4% CAGR. Growth is driven by expanding food packaging demands, e-commerce growth, and versatile industrial applications.
The global polyethylene film market represents one of the largest and most dynamic segments within the global plastics and flexible packaging sector. Valued at USD 92.62 billion in 2025, the market is projected to grow from USD 96.70 billion in 2026 to USD 136.46 billion by 2034, achieving a steady Compound Annual Growth Rate (CAGR) of 4.4% during the forecast period from 2026 to 2034. Polyethylene (PE) films, synthesized from ethylene polymers, offer an exceptional combination of tensile strength, flexibility, moisture resistance, optical clarity, and cost-effectiveness. Consequently, they serve as indispensable packaging and protective materials across a vast spectrum of end-use industries, including food and beverage, agriculture, pharmaceuticals, e-commerce retail, personal care, and building construction.
The steady expansion of the polyethylene film industry is primarily anchored by two powerful macroeconomic catalysts: the continuous growth of the global food and beverage sector and the dramatic surge in e-commerce fulfillment.
The polyethylene film market is categorized across several technical dimensions, including material resin type, manufacturing process, product structure, and end-use application:
From an end-user perspective, the Food & Beverage industry represents the single largest consumer segment, projected to grow at a CAGR of 5.0%. Meanwhile, the Agriculture sector is emerging as the fastest-growing application domain. Agricultural applications—such as greenhouse coverings, high-tunnel structures, soil mulching films, and silage preservation—play a critical role in optimizing crop yields, regulating soil temperature, and conserving water resources, particularly in high-density farming nations.
Geographically, the Asia-Pacific region dominated the global market in 2025 with a commanding 42.35% revenue share. Rapid urbanization, expanding population bases, burgeoning retail markets, and massive agricultural output across China, India, and Southeast Asia continue to drive regional dominance. North America and Europe hold substantial market shares, characterized by advanced recycling infrastructure, high demand for specialized barrier films, and stringent regulatory standards.
While environmental regulations and consumer preferences toward paper-based alternatives pose competitive challenges, the industry is proactively pivoting toward sustainability. Key manufacturing leaders—such as Amcor plc, Berry Global Inc., Sealed Air Corporation, Coveris, Dow Inc., ExxonMobil, Novolex, and Taghleef Industries—are actively developing bio-based polyethylene, chemically recycled resins, and ultra-thin degradable films to mitigate plastic waste while maintaining high packaging performance.
Get the Complete Market Report=https://straitsresearch.com/report/polyethylene-film-market