Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
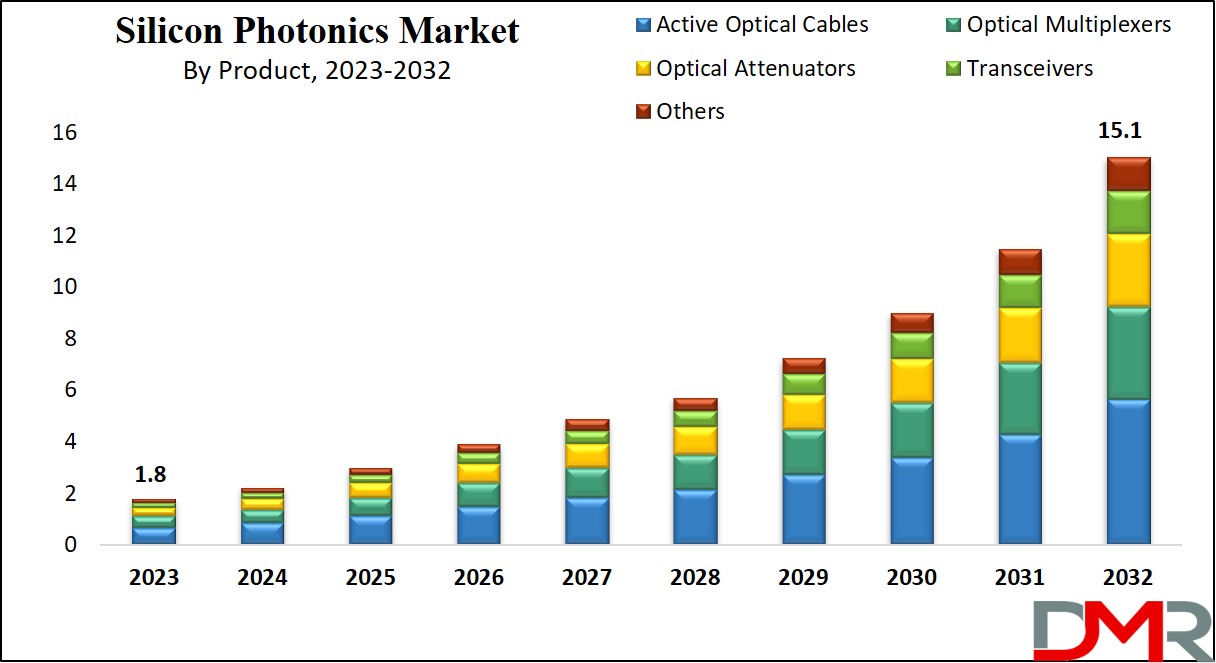
The Silicon Photonics Market is projected to grow from USD 1.8 billion in 2023 to USD 15.1 billion by 2032, registering a 26.7% CAGR during the forecast period. Rising demand for high-speed data transmission, expanding data center infrastructure, 5G networks, cloud computing, artificial intelligence, and high-performance computing is accelerating the adoption of silicon photonics technology.
Silicon photonics combines optical communication technologies with silicon-based semiconductor manufacturing to transmit and process data using light. The technology enables high-speed optical interconnects while supporting compact designs, scalability, and improved energy efficiency.
Growing volumes of data generated by cloud applications, AI workloads, connected devices, and digital services are increasing the need for faster and more efficient communication infrastructure. Silicon photonics is being adopted to address bandwidth limitations and improve data transfer between processors, servers, storage systems, and networks.
The increasing volume of digital data is placing greater demands on communication infrastructure. Traditional electrical interconnects can face limitations related to bandwidth, power consumption, and transmission distance as computing systems become more powerful.
Silicon photonics enables optical data transmission and can support high bandwidth while helping reduce power requirements in data-intensive environments. This is particularly important for hyperscale data centers, cloud computing infrastructure, and high-performance computing systems.
Data centers are a major application area for silicon photonics. Cloud service providers and technology companies require high-speed connections between servers, switches, processors, and storage systems.
Active optical cables, transceivers, optical multiplexers, and other photonic components can support faster data movement across data center infrastructure. As computing workloads become increasingly data-intensive, demand for optical interconnect technologies is creating new opportunities for silicon photonics manufacturers.
The deployment of 5G networks is increasing requirements for high-capacity optical communication. Silicon photonic devices can support high-speed connections across backhaul, metro, and core networks.
Telecommunication operators are also evaluating wavelength-division multiplexing and advanced optical transmission technologies to increase network capacity and improve communication performance.
Download a Complimentary PDF Sample Report:
https://dimensionmarketresearch.com/request-sample/silicon-photonics-market/
One major trend is the integration of photonic and electronic functions on or around the same chip. This approach can reduce the distance between electronic processing and optical communication while supporting more compact and efficient architectures.
Advances in integrated photonic circuits are helping manufacturers improve scalability and create components suitable for high-volume applications.
Co-packaged optics are gaining attention as computing systems require increasingly high-speed connections. Integrating optical components closer to processors and switches can help address bandwidth and power challenges associated with conventional electrical interconnects.
This technology is particularly relevant to AI infrastructure and high-performance computing, where large volumes of data must move rapidly between processing components.
Wavelength-division multiplexing allows multiple optical signals with different wavelengths to travel through the same optical channel. This can significantly increase data transmission capacity without requiring proportional increases in physical fiber infrastructure.
DMR identifies WDM filters as the leading component segment in 2023, with innovation focused on higher integration density, lower insertion loss, reduced crosstalk, and broader wavelength coverage.
Silicon photonics is also moving beyond communication applications. Photonic biosensors can support medical diagnostics, imaging, and point-of-care testing by enabling compact and high-speed detection systems.
Other emerging applications include sensing, autonomous vehicles, edge computing, and advanced imaging systems.
The rapid development of AI infrastructure represents a significant opportunity for silicon photonics. AI systems require extremely high data throughput between processors, memory, storage, and networking equipment.
Optical interconnects can help address these requirements by providing high-bandwidth communication with potential energy-efficiency advantages. Silicon photonics therefore has an expanding role in AI data centers and high-performance computing architectures.
Silicon photonics is being explored for quantum computing applications, where optical technologies can support communication between quantum components and enable specialized photonic processing architectures.
Continued research into photonic integrated circuits and advanced optical components could create additional opportunities in quantum information processing.
Autonomous vehicles require rapid data transmission between sensors, processors, and control systems. Silicon photonics can support applications involving LiDAR, high-speed communication, and real-time data processing.
Edge computing also creates opportunities because devices increasingly need to process and transfer large quantities of information closer to where data is generated.
Growing concern about data center energy consumption is encouraging investment in technologies that can improve computing and communication efficiency. Silicon photonics can help address some of these challenges by moving data optically and reducing reliance on conventional electrical interconnects in suitable applications.
The market is segmented by component, product, and application.
The major components include:
WDM Filters held the leading position in 2023. These components enable multiple wavelength channels to be combined on a single silicon photonic platform, supporting high-capacity optical communication.
Current development efforts focus on increasing integration density, reducing insertion loss and crosstalk, expanding wavelength ranges, and improving manufacturing efficiency.
The product categories include:
Active Optical Cables (AOCs) led the product segment in 2023. Their ability to support high-speed data transmission, scalability, and relatively convenient deployment makes them suitable for high-performance computing and storage applications.
Optical multiplexers are also expected to experience significant development as demand for wavelength-division multiplexing increases.
The market is divided into:
IT & Telecom represented the largest application area in 2023. Data centers, cloud computing, AI workloads, and 5G networks are generating demand for high-speed optical connections and greater network capacity.
Healthcare and life sciences are also adopting photonic technologies for biosensing and diagnostics, while defense applications can benefit from high-speed and secure optical communication.
North America led the market with approximately 49.2% revenue share in 2023. Strong research and development activity, advanced data center infrastructure, major technology companies, and integration of silicon photonics into telecommunications and high-performance computing systems support the region’s position.
Asia Pacific is identified by DMR as the fastest-growing region. China, Japan, South Korea, and Taiwan are investing in silicon photonics research, manufacturing, fabrication capabilities, and commercial applications. Government initiatives, research institutions, and industry collaboration are contributing to regional technology development.
Europe also provides opportunities through investments in telecommunications, advanced computing, semiconductor technologies, healthcare, and photonic research. Other regions are developing applications as demand for high-speed communication and advanced sensing technologies increases.
Purchase the report for comprehensive market details:
https://dimensionmarketresearch.com/checkout/silicon-photonics-market/
Thermal effects represent an important technical challenge for silicon photonics. Silicon absorbs some optical energy, which can generate heat and potentially affect the performance of compact photonic devices.
As electronic and photonic components become increasingly integrated, managing heat becomes more important. High-power laser sources can also create thermal expansion and other performance concerns.
Producing highly integrated photonic devices requires specialized manufacturing processes and precise control over optical and electronic components. Maintaining performance while scaling production can increase technical complexity.
Manufacturers therefore continue to focus on improving fabrication processes, component integration, reliability, and cost efficiency.
Silicon photonic components need to work with existing electronic, optical, and networking infrastructure. Compatibility, packaging, thermal management, and integration requirements can affect adoption and development timelines.
The competitive landscape includes companies such as Cisco Systems, Intel, Marvell Technology Group, STMicroelectronics, Molex, Mellanox Technologies, GlobalFoundries, Finisar, DAS Photonics, and Jupiter Networks.
Companies are focusing on integrated photonic circuits, optical transceivers, active optical cables, WDM technologies, co-packaged optics, and high-speed interconnect solutions. Product development is increasingly centered on improving bandwidth, reducing power consumption, increasing integration density, and supporting AI and data center workloads.
Recent developments cited by DMR include advances in electrically pumped Group IV lasers grown on silicon wafers, co-packaged optics using advanced process technologies, electro-optic polymer integration into silicon photonic circuits, and increased investment in photonic integrated circuit capabilities.
The Silicon Photonics Market is projected to grow from USD 1.8 billion in 2023 to USD 15.1 billion by 2032, registering a CAGR of 26.7%.
WDM Filters held the leading position in 2023, supported by their role in combining multiple wavelength channels for high-capacity optical communication.
Active Optical Cables led the product segment in 2023. Their scalability, cost-effectiveness, and suitability for high-performance computing and storage contribute to their adoption.
IT & Telecom is the largest application area, supported by data center expansion, cloud computing, 5G networks, AI workloads, and growing bandwidth requirements.
North America accounted for approximately 49.2% of revenue in 2023, while Asia Pacific is identified as the fastest-growing regional market.
The Silicon Photonics Market is projected to expand from USD 1.8 billion in 2023 to USD 15.1 billion by 2032, reflecting a 26.7% CAGR. Increasing data volumes, AI workloads, cloud computing, 5G deployment, and high-performance computing are creating strong demand for high-speed optical interconnect technologies.
WDM filters, active optical cables, and IT and telecom applications remain important areas of the market, while emerging opportunities in AI infrastructure, quantum computing, healthcare, autonomous vehicles, and edge computing are broadening the technology’s use cases.
Continued advances in photonic integration, co-packaged optics, laser technologies, thermal management, and manufacturing processes are expected to influence the next stage of market development.