Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
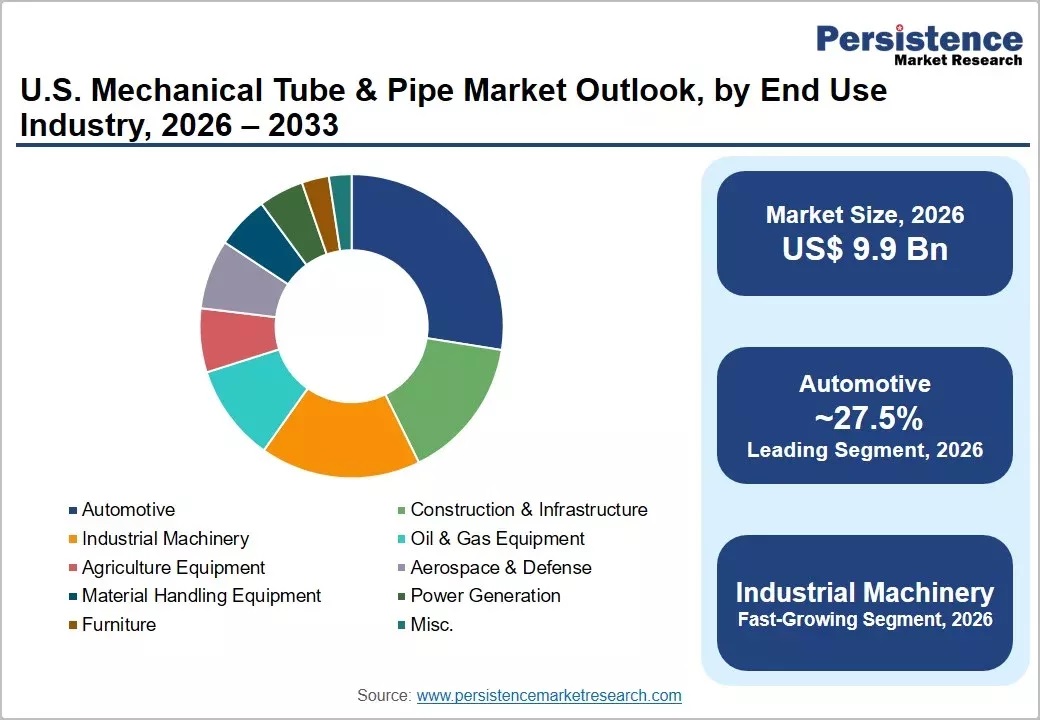
The U.S. mechanical tube & pipe market size is expected to be valued at US$ 9.9 billion in 2026 and projected to reach US$ 14.6 billion by 2033, growing at a CAGR of 5.7% between 2026 and 2033. Robust demand from automotive manufacturing, industrial machinery, and infrastructure development is supporting market expansion. Investment associated with the Infrastructure Investment and Jobs Act (IIJA) is also encouraging domestic manufacturing activity and demand for durable steel components.
Mechanical tubes and pipes are engineered products used in structural assemblies, automotive components, machinery, and precision manufacturing applications. Carbon steel tubing represents an important product category because of its strength, versatility, and cost effectiveness. The Midwest remains a significant regional manufacturing center, supported by automotive production, metalworking expertise, and established industrial supply chains. Increasing demand for lightweight components, dimensional accuracy, and dependable material performance is influencing purchasing decisions.
𝐅𝐫𝐞𝐞 𝐒𝐚𝐦𝐩𝐥𝐞 & 𝐂𝐡𝐞𝐜𝐤 𝐭𝐡𝐞 𝐋𝐚𝐭𝐞𝐬𝐭 𝐌𝐚𝐫𝐤𝐞𝐭 𝐀𝐧𝐚𝐥𝐲𝐬𝐢𝐬:https://www.persistencemarketresearch.com/samples/37404
Key Highlights from the Report
Market Segmentation: Product Materials and Industrial Applications
The U.S. mechanical tube & pipe market can be examined through material type, manufacturing process, and end-use application. Carbon steel tubes are widely used in automotive structures, machinery, and industrial equipment because they offer mechanical strength and manufacturing flexibility. Alloy steel products address applications requiring specialized performance characteristics, while stainless steel tubing supports environments where corrosion resistance and durability are important. Material selection depends on strength requirements, fabrication methods, operating conditions, and cost considerations.
Manufacturing processes include seamless and welded tube production. Seamless mechanical tubing serves applications requiring consistent material properties and demanding mechanical performance. Welded tubing offers manufacturing efficiency and versatility across numerous industrial uses. Automotive manufacturing represents an important end-use sector, followed by industrial machinery, construction equipment, agricultural machinery, and general fabrication. Customers increasingly seek products with accurate dimensions, consistent wall thickness, dependable surface quality, and compatibility with automated manufacturing processes.
Regional Insights: Manufacturing Clusters Shape Domestic Demand
The Midwest represents a significant demand center because of its concentration of automotive manufacturers, industrial equipment producers, and metal fabrication businesses. States including Michigan, Ohio, Indiana, and Illinois maintain established manufacturing networks that support mechanical tubing consumption. Proximity to processing facilities, distributors, and major industrial customers contributes to efficient supply arrangements and shorter delivery distances.
The Southern United States is gaining importance through automotive assembly operations, industrial investment, and expanding manufacturing facilities. States including Tennessee, Alabama, Georgia, and South Carolina provide opportunities for tubing suppliers serving automotive and machinery customers. Western states support demand through aerospace manufacturing, specialized engineering, and infrastructure development. Regional purchasing patterns vary according to industrial specialization, transportation requirements, and project activity.
Market Drivers: Automotive Production and Infrastructure Modernization
Automotive manufacturing remains a major driver of mechanical tube and pipe demand. Manufacturers use precision tubing in chassis assemblies, suspension components, steering systems, structural supports, and other mechanical applications. Increasing emphasis on vehicle performance, durability, and weight optimization encourages demand for materials offering reliable mechanical properties.
Infrastructure modernization provides another important demand opportunity. Federal investment associated with the IIJA supports transportation networks, bridges, utilities, and related construction activities. Although not every infrastructure project directly requires mechanical tubing, increased equipment manufacturing and industrial fabrication can generate additional demand. Domestic production investments and industrial modernization further encourage manufacturers to evaluate reliable American supply chains.
Market Restraints: Material Costs and Competitive Pressures
Raw material price volatility represents a significant challenge for mechanical tubing manufacturers. Changes in steel prices, energy expenses, and transportation costs can affect production margins and customer purchasing decisions. Manufacturers must also manage competition from imported products, fluctuating industrial demand, and changing trade requirements.
Production complexity creates additional challenges. Precision mechanical tubing requires careful control of dimensions, mechanical properties, and surface quality. Investments in advanced processing equipment, inspection systems, and skilled personnel can increase operating expenses. Smaller suppliers may face difficulties maintaining competitive pricing while meeting demanding customer specifications.
Market Opportunities: Advanced Manufacturing and Domestic Supply Chains
Growing investment in domestic manufacturing presents opportunities for mechanical tube and pipe suppliers. Automotive electrification, industrial automation, and infrastructure modernization encourage demand for specialized tubing products. Manufacturers capable of producing high-strength, lightweight, and precisely dimensioned components can address evolving engineering requirements.
Supply chain localization offers another opportunity. Industrial customers increasingly evaluate sourcing reliability, delivery schedules, and supplier responsiveness. Domestic manufacturers offering customized production, dependable quality, and technical assistance can strengthen relationships with automotive and industrial equipment producers.
Company Insights: Competitive Landscape and Key Players
The U.S. mechanical tube & pipe market includes established steel manufacturers, specialized tubing producers, and industrial suppliers. Competition focuses on material quality, production capabilities, customization, delivery reliability, and customer support. Companies active in the industry include:
These companies support industrial demand through steel production, tubing manufacturing, processing services, and distribution capabilities.
Recent Developments: Investments and Industry Modernization
In September 2026, Zekelman Industries launched a national sourcing campaign focused on simplifying procurement for mission-critical projects. The initiative highlighted domestic manufacturing capabilities and the importance of dependable steel supply chains for infrastructure development. <Cite ref=”turn849241search1″/>
In August 2026, Cleveland-Cliffs announced a planned US$ 1 billion investment at Middletown Works, supported by a proposed US$ 500 million U.S. Department of Energy award. The investment reflects ongoing efforts to modernize domestic steelmaking infrastructure, although it is not specifically a mechanical tubing expansion. <Cite ref=”turn849241search12″/>
Conclusion: Strengthening America’s Industrial Manufacturing Future
The U.S. mechanical tube & pipe market offers opportunities through automotive manufacturing, infrastructure investment, and industrial modernization. Increasing requirements for durable, precision-engineered tubing will encourage manufacturers to improve production efficiency, material performance, and product customization.
However, successful growth requires effective cost management, dependable supply chains, and consistent manufacturing quality. Suppliers investing in advanced processing technologies, technical expertise, and customer relationships will be better positioned to address evolving industrial requirements through 2033.